 Capital Kings LLC
Finished One Build?Bring Less Cash to Your Next One.
Up to 95% of lot and construction costs with a financed interest reserve, for builders with one completed build in their LLC.
Finished one ground-up build in your own LLC? You may qualify for up to 95% of your lot and construction costs, including a financed interest reserve. That can reduce the cash you need to bring to the project, while interest is charged only on funds that have been drawn.
See if your next build fits the program.
Financed Interest Reserve: your first months of interest are financed as part of the loan rather than paid out of pocket.
Example rate: 9.50%. Based on the real Oklahoma City deal shown below. Pricing varies by borrower, project and market.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
- Lot, at closing$31,500
- Build, in draws$199,243
- Interest reserve$11,507
- You bring$24,257
With one completed build in your own LLC, the lender can fund up to 95% of the lot and build when you count the financed interest reserve. That is not 5% down: about 90% of the lot and build comes from the lender in cash, so on the example you bring about 10% of the lot and build plus closing costs. The loan is capped at 75% of the finished value, the reserve covers your interest payments for roughly the first 8 to 10 months, and interest is charged only on what has been drawn.
Capital Kings is a broker, not the lender. We compare construction lenders and structure the deal around the project. The example below comes from an actual lender offer we received for an Oklahoma City build.
Terms at a glance
| Loan to cost | Up to 95% with the financed interest reserveAbout 90% of lot + build in cash |
|---|---|
| Completed value cap | 75% of the appraised finished valueCovers the whole loan, reserve included |
| Rate | 9.50%, interest only on what has been drawn |
| Origination | 3.00% originationWhat the lender charged on the real deal. Your term sheet lists your exact number. |
| Lender fees | About $3,500 on the real dealUnderwriting and processing, on top of the origination |
| Broker fee | Capital Kings broker fee: 1% ($2,000 minimum, $10,000 maximum). This is the only fee Capital Kings earns on the loan, and on bigger loans it is open to negotiation (never below $2,000). |
| Term | 12 months on the real deal15 months on the builder-backed version |
| Lot advance day one | 70% of the lot with permits in hand60% with a feasibility study instead |
| Construction funding | The build budget, paid in reimbursement drawsNo minimum draw. Inspector out in 24 to 48 hours, funds 3 to 5 business days later. |
| Interest reserve | 6 months of fully drawn interest, financedIt makes your payments first. You repay it at sale or refinance. |
| Cash requirement | $13,500 lot down + $10,757 of the build + closing costsOn the example. The lender checks for about $26,900 in the bank; your cash to close covers it. |
| Experience | 1 completed build in your LLCOr a general contractor with 5+ completed builds |
| Credit | 680+The real deal behind the example was 690. |
| States | 37 statesNot offered in Alaska |
| Close time | As fast as 14 daysThe lender’s written offer in about a day |
These terms come from a lender’s letter of intent (their written offer) on a real deal. Rate and fees can move with your file and the market; the lender’s offer on your deal is the final word.
One Oklahoma City build, numbers changed
$45,000 lot, $210,000 build, $330,000 finished value, 690 credit, one finished build in the borrower’s LLC, 12 months. Based on a real deal we priced in Oklahoma City, with the dollar amounts changed. The terms are the real ones.
Plus closing costs: 3.00% origination (about $7,300), lender fees of about $3,500, our $2,423 broker fee, title, insurance and the appraisal.
The terms, on this example
| Rate | 9.50%, on drawn funds only |
| Lot at closing | 70%, permits in hand |
| Lot + build | 95% with the reserve, the cap that set the loan |
| Finished value | 73.4%, under the 75% cap |
| First payment | About $249 |
| Lender’s cash check | About $26,900 (10% of the build plus fees), already covered by your cash to close and your share of the build |
| No permits yet | 60% of the lot, $18,000 down |
How does the interest reserve work?
The interest reserve is money borrowed at closing to cover your early loan payments. You don’t receive the entire construction loan on day one. As construction draws are funded, your interest payment increases. The reserve covers those payments first, so you aren’t writing a monthly interest check during the early part of the build.
On the example, the payment starts around $249 a month (interest on the lot advance) and climbs with each draw to about $1,920 a month fully drawn. The reserve is six of those fully drawn payments, $11,507, and because the early payments are smaller it stretches to about 8 to 10 months.
The example with the build drawn evenly over 8 months: the reserve covers about 10 months. A faster build uses it sooner. Every term sheet shows your starting and fully drawn monthly payment, so you can estimate yours. It isn’t free money: it’s part of the loan, repaid when you sell or refinance.
Where does every dollar go?
Your term sheet shows every fee, who it’s paid to, your cash to close, and your starting and fully drawn monthly payment. Here is the example on both structures.
- Land down paymentEquity$13,500
- Appraisal feeAppraiser$550
- Prepaid interestLender$123
- Lender fees: origination, underwriting, processingLender$10,758
- Broker feeBroker$2,423
- Closing / titleTitle co$3,533
- Builder’s risk insurance (estimate)Insurer$1,580
The $11,507 interest reserve is inside the $242,250 loan, not in your cash to close. Proof of funds ($43,224) is your cash to close plus the part of the build you pay, which already covers the lender’s cash check of 10% of the build plus fees. You pay $10,757 of the build yourself as it goes up. The gold broker line is the only money Capital Kings earns.
- Land down paymentEquity$38,250
- Appraisal feeAppraiser$550
- Prepaid interestLender$29
- Lender origination and feesLender$5,635
- Broker feeBroker$2,168
- Closing / titleTitle co$3,407
- Builder’s risk insurance (estimate)Insurer$1,580
Lower fees: 10.49% and 2% origination, 85% of lot + build, no interest reserve. You pay the interest yourself from the first month, and more of the lot is yours: $38,250 down.
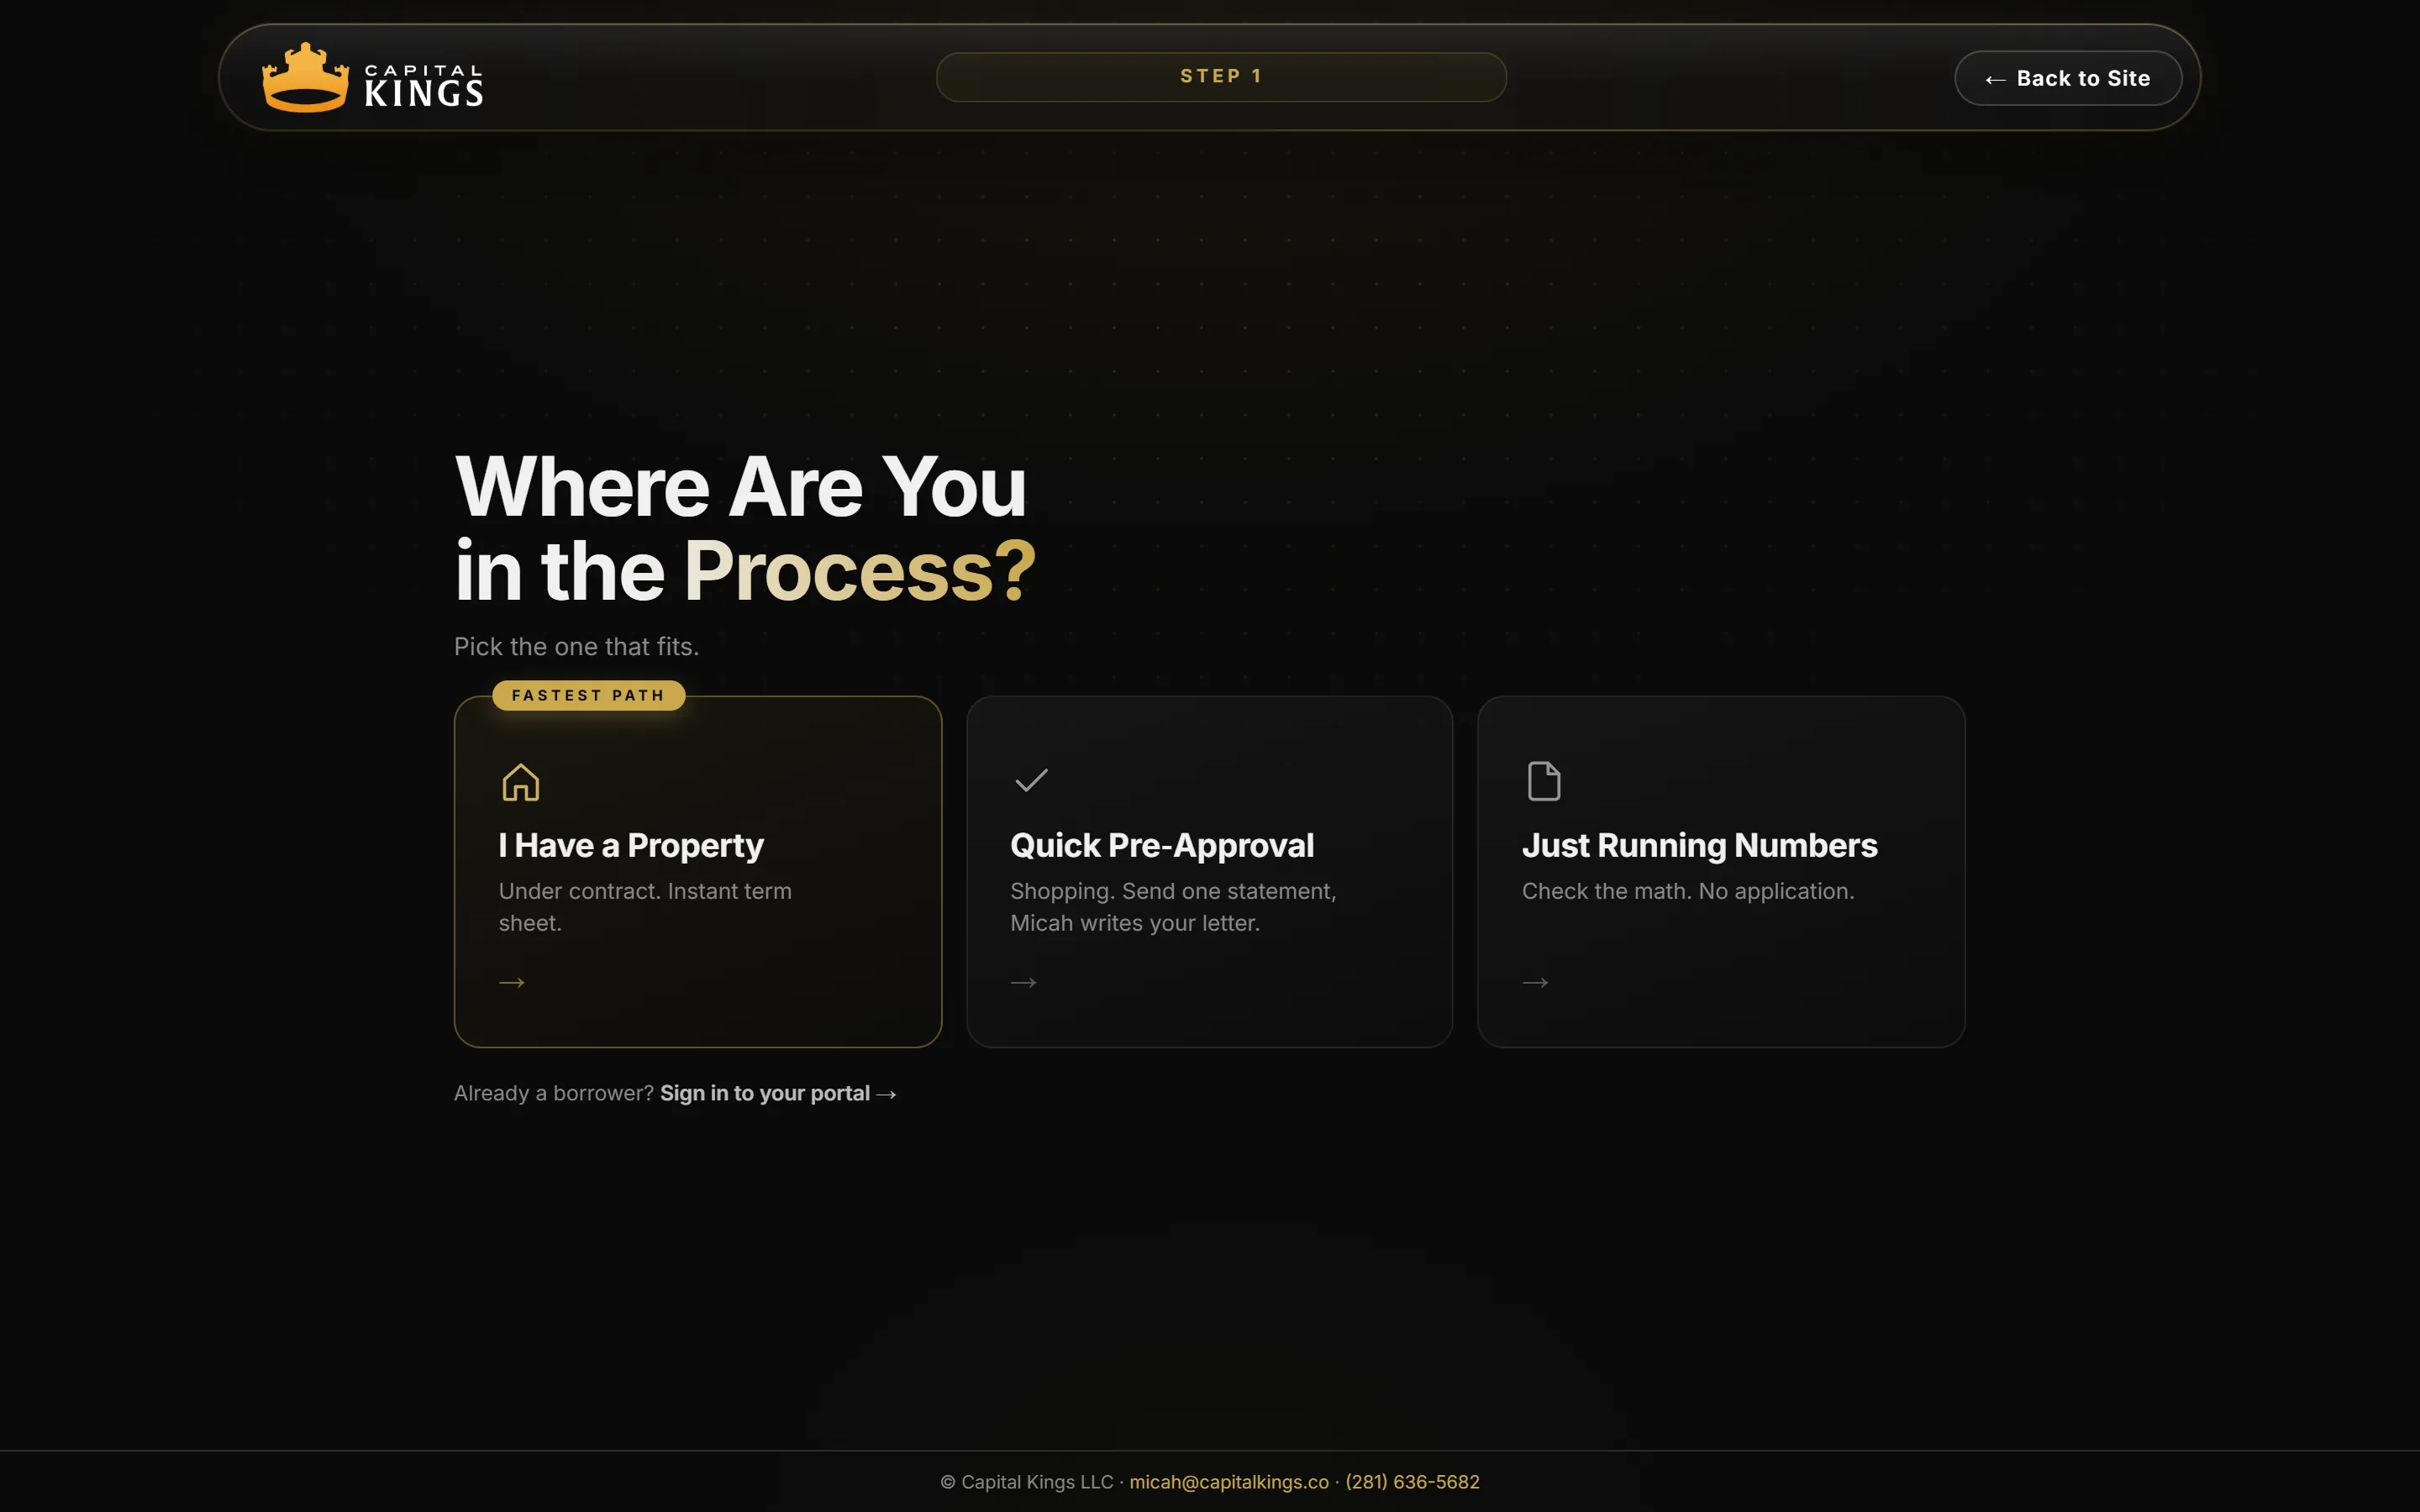
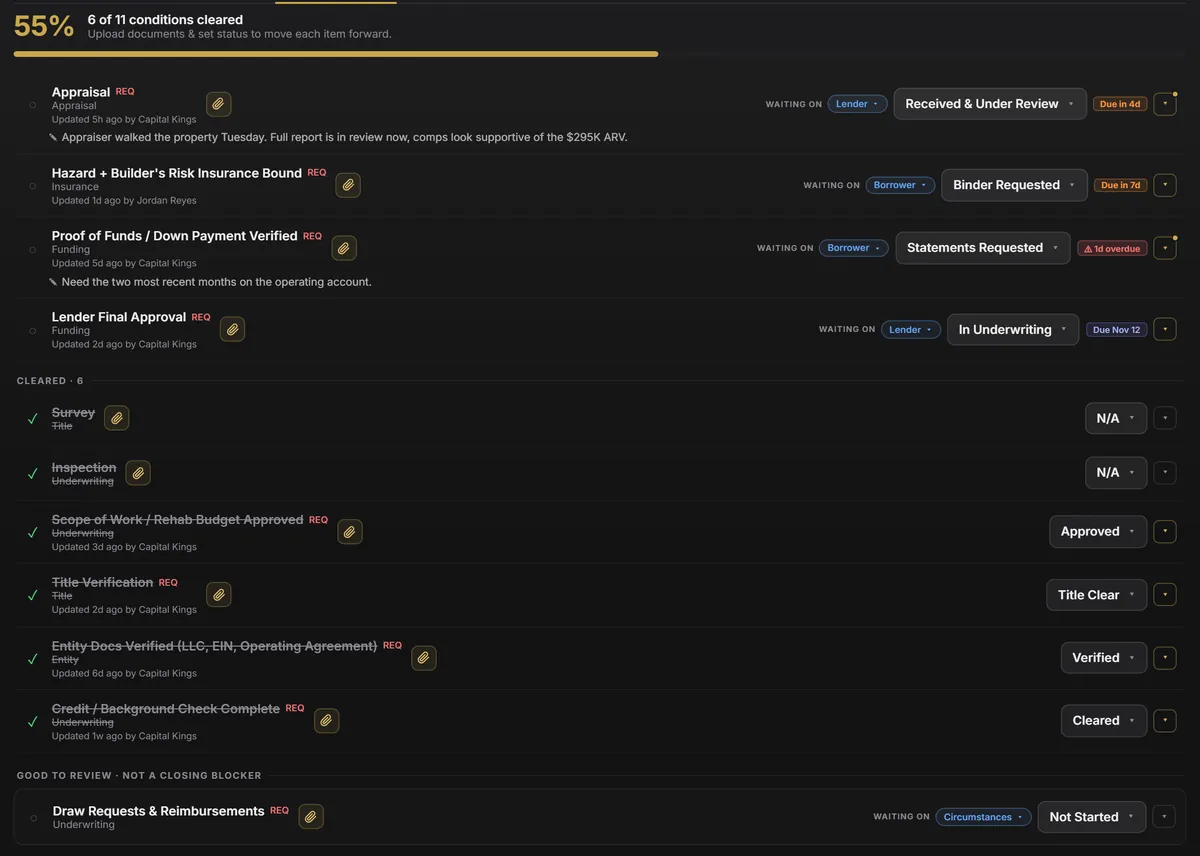
Sample sheets for a made-up borrower on the example’s numbers, built by the same system that builds yours. No credit pull to get started.
After you apply, every condition and document sits in your borrower portal.
Your track record, or your builder’s
Your builder has 5+
One build in your LLC
3 builds in 3 years
What proves a build
- Your LLC on title of the finished house.
- The permit and the certificate of occupancy (the city’s sign-off that it’s done).
- A track record sheet: address, start date, finish date and budget.
- Using a builder’s record: the GC contract, license and their builds from the last 3 years. The GC doesn’t sign the loan.
The exception: your first ground-up build if you’re acting as your own contractor. For that first project, you’ll need an experienced GC. After you complete it, your track record can qualify you for the program.
Available in 37 states
Select a state to see the local construction program. Not offered in Alaska.
Size your build on these terms
Prefilled with the example. It runs the program’s terms: 70% of the lot (60% without permits), 75% of the finished value, a six-month interest reserve, 9.50% and 3.00% origination.
Sizing your build on the same terms as the application. Price my next build →
Less cash or lower fees: which fits your build?
Lower cash in, lower fees, and lower monthly carrying costs don’t always come together. Here are the two ways we can structure the loan, on the example.
On a first build, with a general contractor who has 5 or more completed builds, you have two options: Lower Fees at 85% of cost and 11.74% (12.24% below a 740 score) at 2% origination, or the Financed Interest Reserve at about 86% of the lot and build in cash (90% with the interest reserve included) at 9.50%, with 3% origination plus lender fees.
On this build the Financed Interest Reserve takes $22,586 less cash to close but leaves $22,901 more of the build to you before the first draw, needs $44,312 less proof of funds, and costs $4,090 more in origination and lender fees at closing.
After one completed build you have two options: Lower Fees stays at 85% of cost with the rate dropping to 10.49% at 2% origination, or the Financed Interest Reserve goes to about 90% of the lot and build in cash (95% with the interest reserve included) at 9.50%, with 3% origination plus lender fees.
On this build the Financed Interest Reserve takes $19,152 less cash to close but leaves $10,757 more of the build to you before the first draw, needs $51,264 less proof of funds, and costs $5,123 more in origination and lender fees at closing.
Both columns run this page’s worked example ($45,000 lot, $210,000 build, $330,000 finished value, 690 credit), priced the same way as your term sheet, as of October 2026. Where a structure leaves part of the build to you, that amount sits under its cash to close. We price your build on both and you pick. These are two structures available through our lending network, not a comparison of every lender or program we offer.
Construction loan FAQ
How much cash do I need for my second build?
Does 95% loan to cost with an interest reserve mean I only bring 5%?
What is an interest reserve and who pays it back?
Does my one build have to be in my LLC?
Can my builder’s experience count instead of mine?
Can I pull permits before I own the lot?
How do draws work and how fast do they fund?
Which states is this available in?
What credit score do I need?
Is Capital Kings the lender?
Which questions have worked examples?
Before you break ground
Finished One Build? Let’s Price the Next One.
About five minutes to apply. We’ll send the deal to our lending partners and show you the available structure, cash requirement and fees. No credit pull to get started.