 Capital Kings LLC · Non-QM Mortgage Broker
Hard Money Lenders inMount Pleasant, South Carolina
Fix and flip, DSCR rental and new construction financing for Mount Pleasant investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
Price a Mount Pleasant deal right now
Prefilled with a realistic Mount Pleasant deal. Change any number and it reprices on the programs that lend in South Carolina, with the same math as our term sheets.
Sizing your flip on the same terms as the term sheet. Get a real term sheet →
Financing a deal in Mount Pleasant
Mount Pleasant is the affluent town across the Ravenel Bridge from Charleston. Strong schools, the marsh views and a short drive to downtown make it one of the most expensive places in the state. Flips here are large: 1970s and 1980s houses in Snee Farm, Hobcaw Point and Shemwood that need a full update to match newer neighborhoods.
East of the Cooper, the lot is the asset. A 1980s house backing onto marsh, a pond or the golf course in Snee Farm trades far above the same floor plan facing a busy connector road, and buyers will pay to fix a dated interior on the right lot. We look at the view, the elevation and the street before the kitchen, then size the after repair value on renovated houses with the same setting.
What a Mount Pleasant deal looks like on paper
Mount Pleasant example: $680,000 purchase, $110,000 rehab, $1,130,000 after repair value, 700 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Say a 1980s two-story in Snee Farm with an original kitchen, wallpaper in the baths, a screened porch that needs rebuilding and an old HVAC system. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$102,000
- Origination (0.5%)Lender$3,440
- Lender fees (flat)Lender$1,989
- Broker fee (1%)Broker$5,940
- Title and closing (estimate at Texas rates)Title$5,735
- Prepaid interest (15 days)Lender$2,254
- Property insuranceInsurer$7,505
- AppraisalAppraiser$550
Interest while you rehab: $4,571 a month on the $578,000 funded at closing, $5,441 once every draw is out. Proof of funds is cash to close plus $27,500 of rehab reserve and $32,646 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
Fix and flip programs in Mount Pleasant
Swipe the table for rates, credit and terms →
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% of purchase | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 70% of ARV | 12 months | 5-14 days |
| First Flip, 10% Down1 | 10% of purchase + rehab | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips2 | 7.5% of purchase + rehab | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 5+ Flips3 | 5% of purchase | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| 100% Financing, 2+ Flips4 | 0% (100% financing) | 620+ | 2+ completed flips | 9.50% to 12.00% | 2.5% | 70% of ARV | 9 months | 7-14 days |
| Fastest Close (3 days) | 10% of purchase | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Rate 9.99% with 2% to 2.25% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% with 1.5% to 1.75% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
- Needs 2 completed flips in the last two years and about $75,000 in verified liquidity. Rate 9.5% to 12% with 2% to 3% origination, set per file. Purchase plus rehab must fit under 70% of ARV.
Origination has a $2,000 minimum on most programs (a few lenders set a higher one, noted above) and our broker fee is 1% with a $2,000 minimum and a $10,000 maximum. These are the numbers our term sheets use as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
Where Mount Pleasant prices sit right now
Before we price a Mount Pleasant flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the Mount Pleasant median sale price at $920K for the three months ending September 2026, up 2.2% on a year earlier, with homes selling in around 70 days. The median price per square foot is $405.
| Median sale price (Redfin) | $920K |
| Change from a year earlier | up 2.2% |
| Days on market (Redfin) | 70 |
| Median price per square foot | $405 |
How a Mount Pleasant file actually gets priced
Appraisers in Mount Pleasant match on subdivision, flood zone and lot, especially marsh or water views. Loans here are large, so a small percentage miss is a big dollar figure. We use recent closings in the same neighborhood and stay out of Charleston and Daniel Island comps. A South Carolina attorney runs the closing, so line one up early.
Much of Mount Pleasant sits near the marsh and Shem Creek, so check the flood zone and elevation; a big rehab in a mapped zone can trigger the substantial improvement rule. The town has a tree protection ordinance that limits removing large trees, which can affect additions or driveways. The Old Village is a historic district with its own review for exterior work. Many subdivisions have HOAs with design approval.
Who buys your finished Mount Pleasant deal
The finished Mount Pleasant house sells to a family moving for the East Cooper public schools, a physician commuting over the bridge to MUSC, or an out-of-state buyer trading a Northeast house for the marsh. Many skip financing altogether. Screened porches, outdoor kitchens and storage for boats and bikes matter here as much as the inside. Short-term rentals face strict town rules, so check before you count on one, and plan for a retail sale.
What happens after you apply
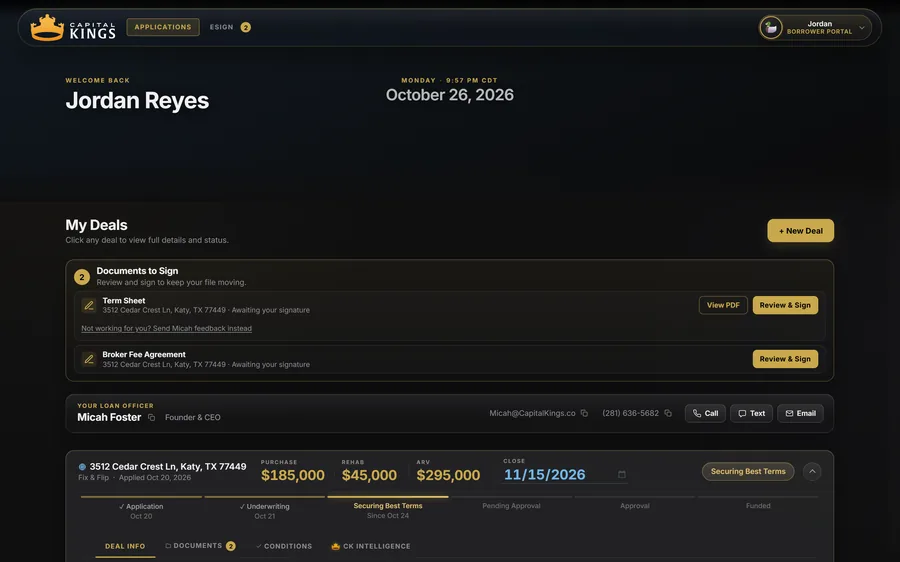
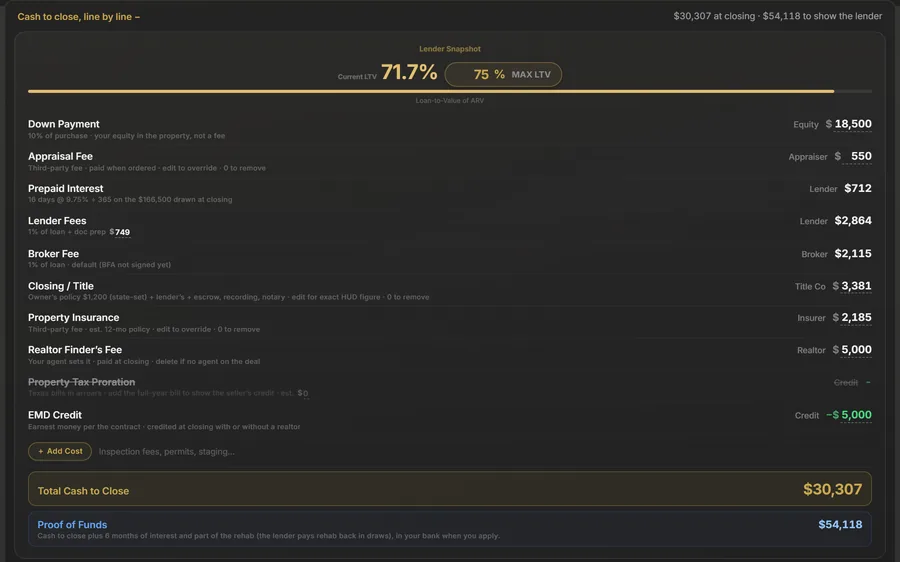
Apply once and the whole Mount Pleasant loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
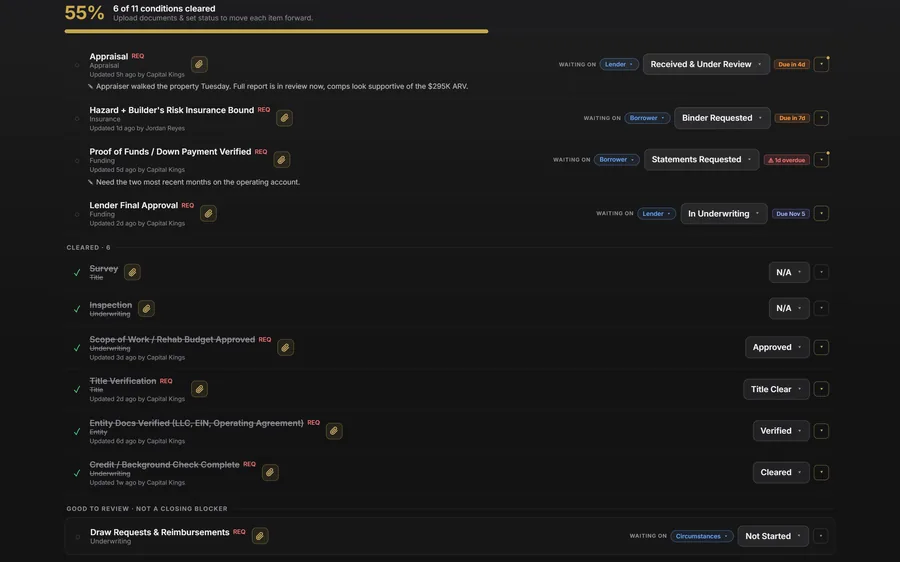
The full walkthrough is on how it works, and you can tour the borrower portal before you apply.
What we fund in Mount Pleasant
Fix and flip
- Rates
- from 8.99% at 760+ credit
- With experience
- 0% down with 2+ completed flips, purchase plus rehab under 70% of ARV
- Rehab
- 100% funded, paid in draws
Rental (DSCR)
- Qualify on
- the rent, no W-2s or tax returns
- Down
- from 20% at 700+ credit
- Good for
- buy-and-hold, and the refinance when a flip becomes a rental
New construction
- Rates
- from 8.49% with 5+ completed builds
- First build
- 85% of cost with a GC who has 5+ builds
- Builds
- single family to small multifamily
Where we lend in Mount Pleasant
We broker deals across the whole Mount Pleasant market. The submarkets investors ask us about most are Old Village (29464), Snee Farm (29464), Hobcaw Point and Shemwood (29464), Brickyard and Park West (29466), I’On (29464) and Belle Hall (29464).
How long does a Mount Pleasant loan take to fund?
You send the address, purchase price, rehab budget and your ARV, which takes about five minutes and no credit pull. We take it to the lenders in our network that fit it and are licensed in South Carolina, and the rate, origination, leverage and cash to close come back side by side. 5-14 days to fund, as little as 72 hours on the fastest programs. We stay on title and the lender through funding.
Mount Pleasant hard money FAQ
Do you lend hard money in Mount Pleasant?
Which fix and flip programs apply in Mount Pleasant?
How fast can a Mount Pleasant hard money loan close?
How much do I need to bring to close on a Mount Pleasant flip?
Do you fund the rehab budget in Mount Pleasant?
What credit score do I need for a Mount Pleasant fix and flip loan?
Can I refinance a Mount Pleasant flip into a rental loan?
Can I remove trees on a Mount Pleasant lot?
Does a marsh or pond view change the after repair value in Mount Pleasant?
What to read before you sign a term sheet
- How construction draws and the rehab holdback actually work
- Dutch vs standard interest: what it really costs you
- Cash to close on a flip: the number most investors miss
- How to get an instant hard money term sheet
Hard money near Mount Pleasant: Charleston, Myrtle Beach and Savannah. More South Carolina city guides: Columbia, Florence, Greenville and Hilton Head Island. Or see everything we fund in South Carolina.
Ready to fund your Mount Pleasant deal?
Submit your scenario in about 5 minutes. We shop it and come back with real terms, not a generic rate sheet.