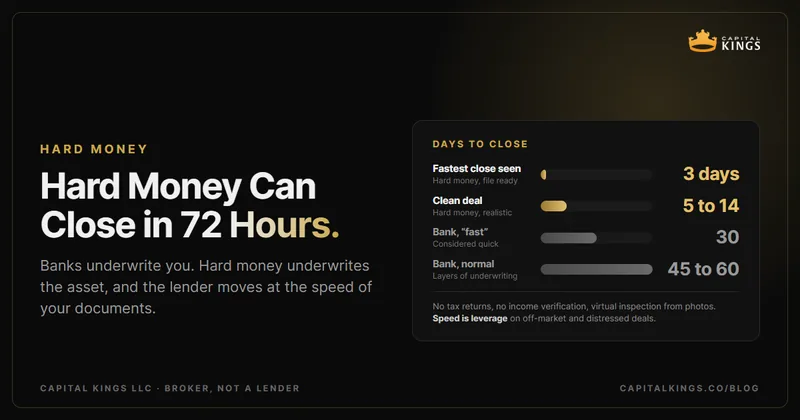
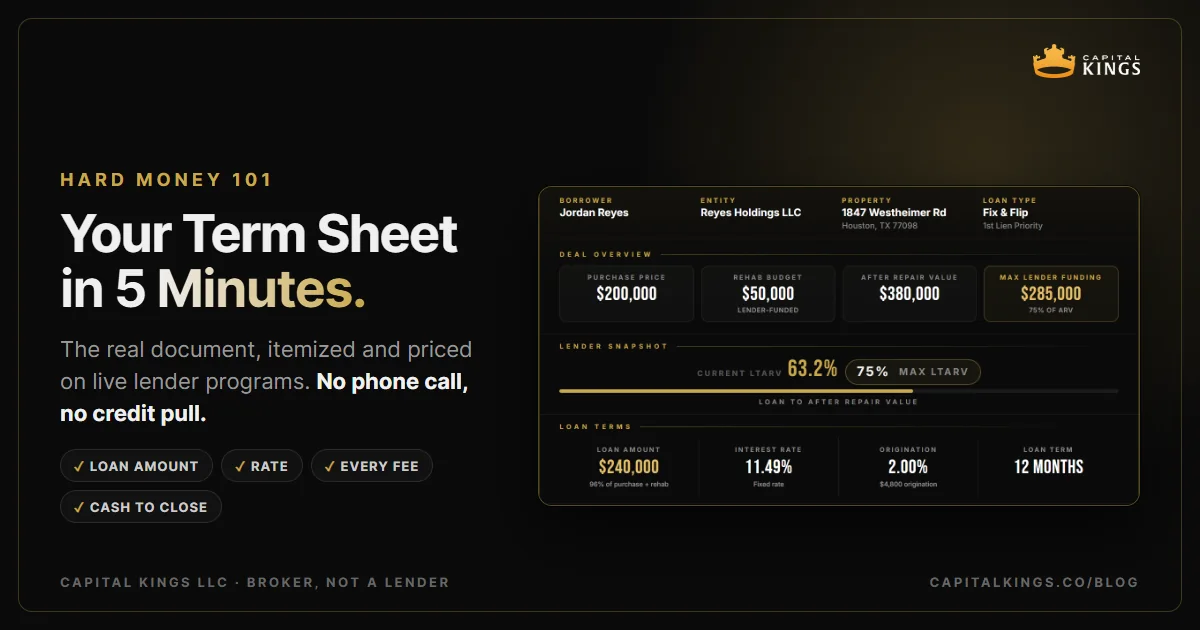
When you're chasing a deal, the money is usually the slowest part. You find a property, the clock starts, and you still don't know what your loan looks like or how much cash you'll need to bring. Most lenders want a phone call first, and then you wait a day or two just for a ballpark. The instant term sheet skips that wait. You type in your deal, and about five minutes later you've got an itemized document priced on our own program pricing, which we keep calibrated to what our lenders charge, before you've talked to anyone.
What the Term Sheet Shows You
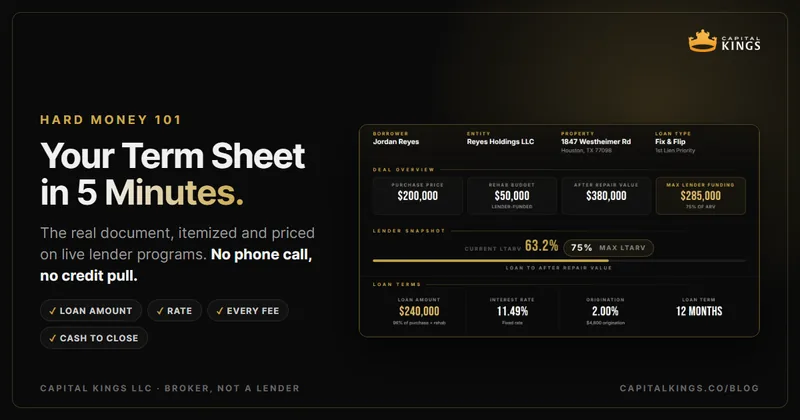
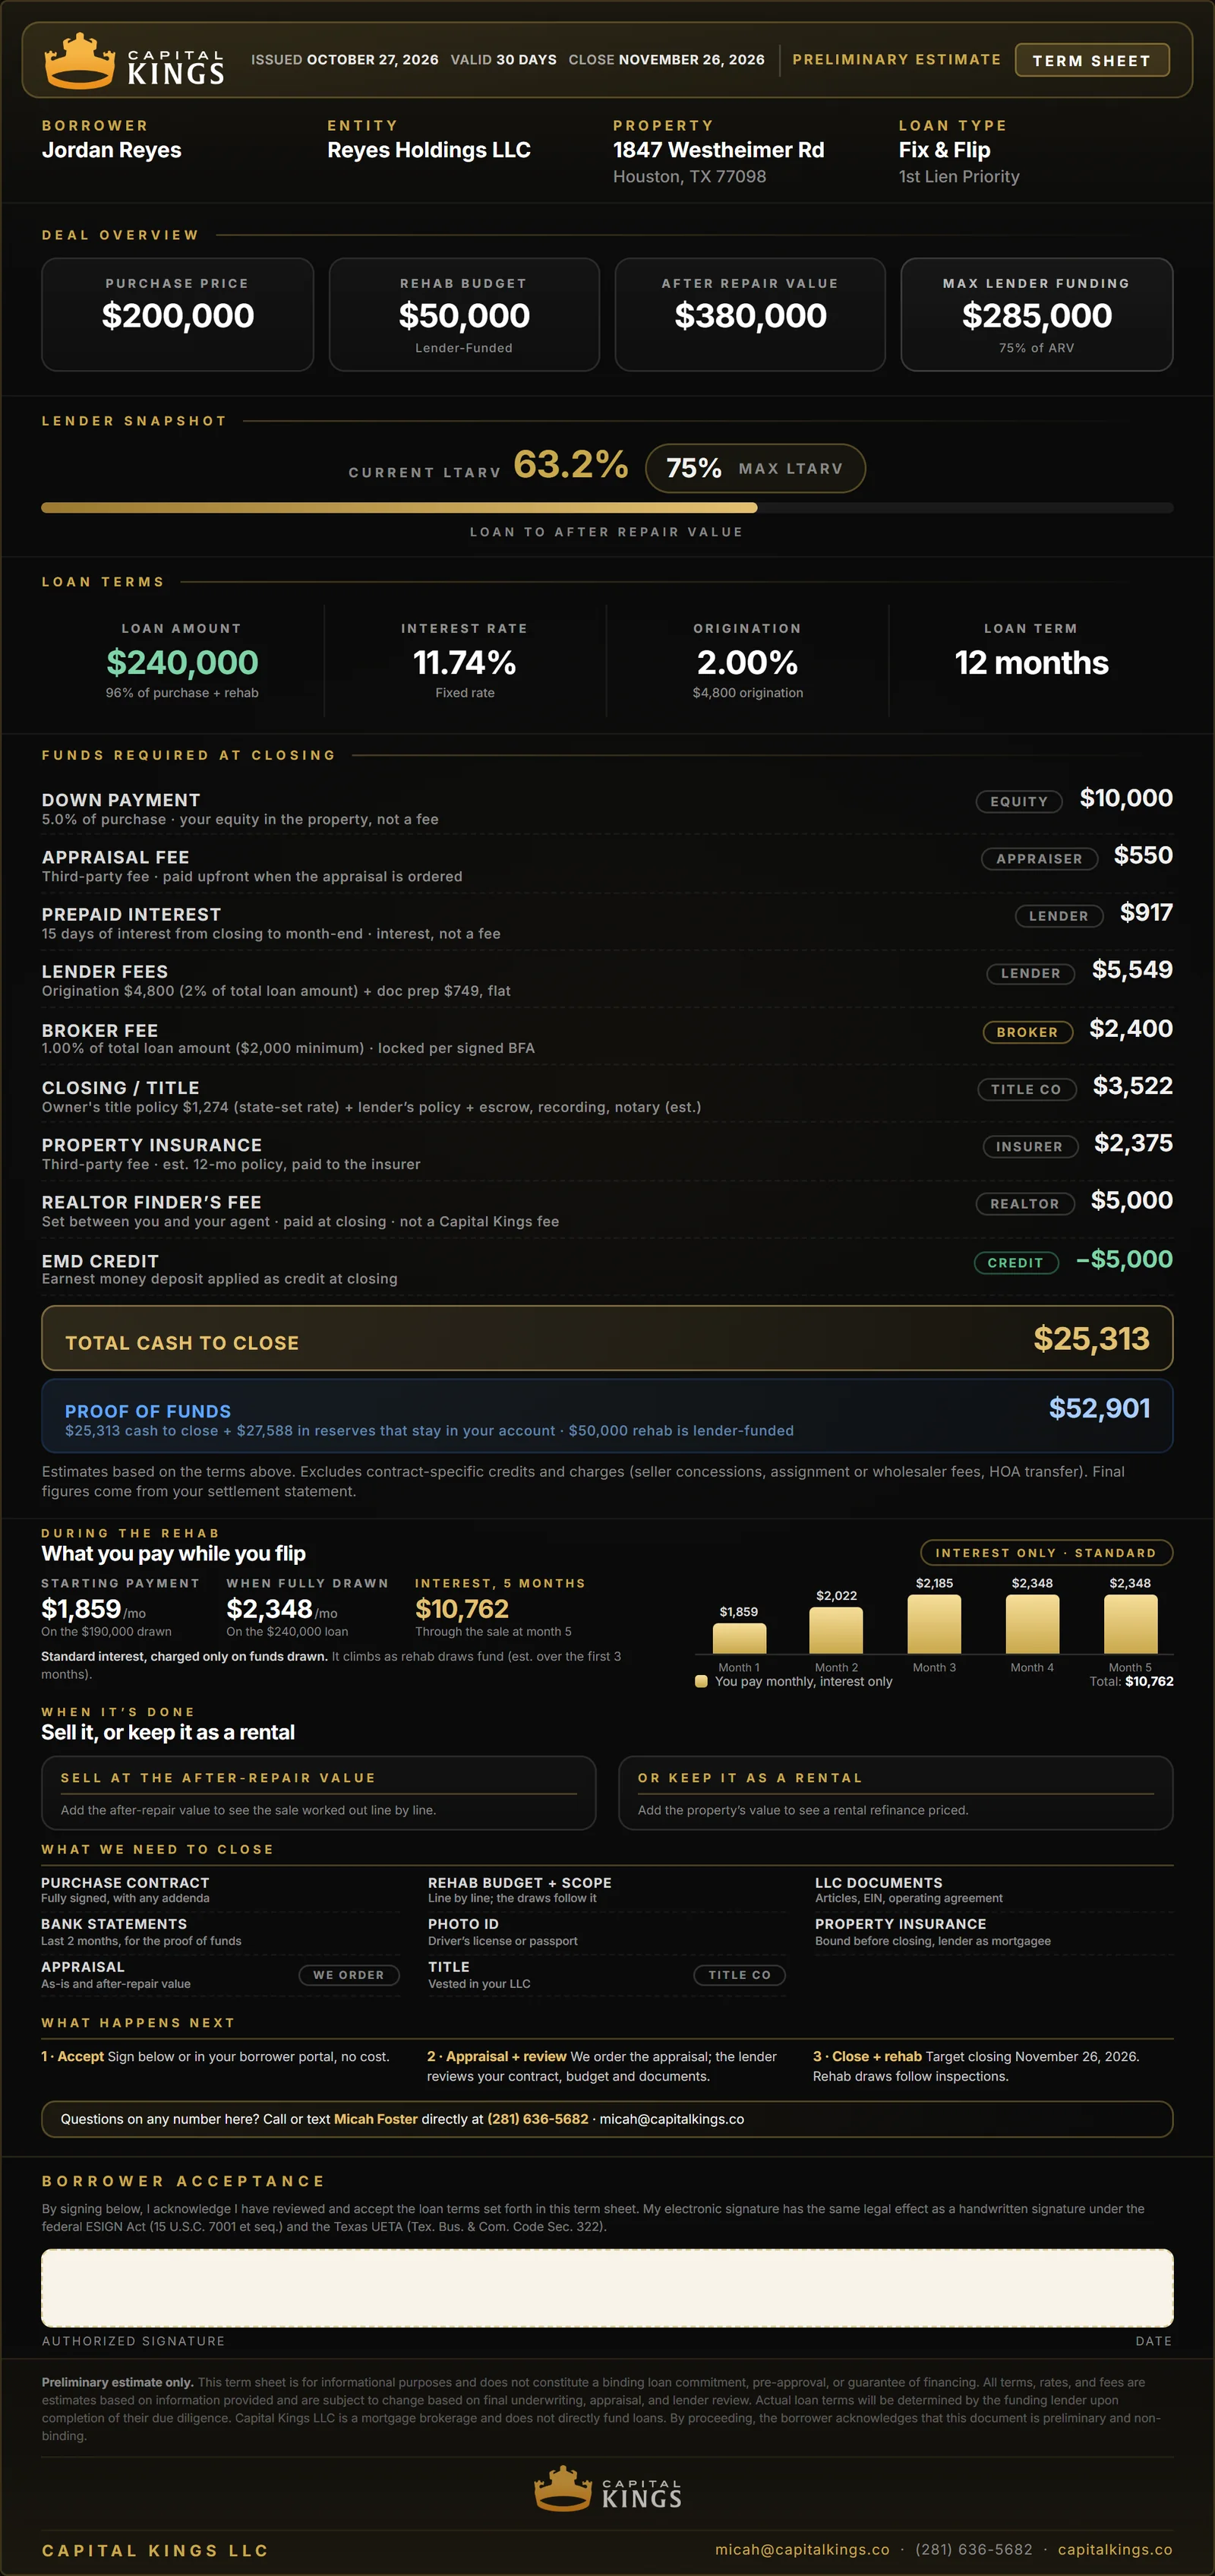
What you get back is a full term sheet with your name and your property on it. Here's what it shows:
- Your loan amount and how it's built: a percentage of the purchase price plus your rehab budget
- The interest rate and loan term
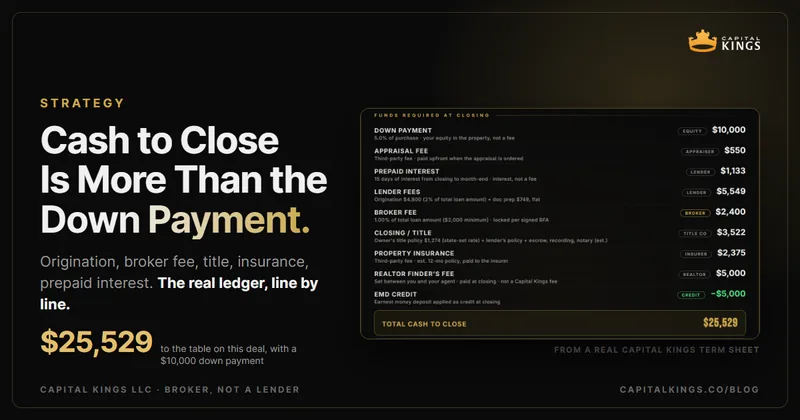
- Your down payment and every fee, each on its own line: origination, broker fee, title and closing
- Your cash to close, the actual number you wire at the closing table
- The proof of funds a lender will want to see in your account
- Your estimated monthly payment, both when the loan first funds and at full draw, once all your rehab money has been released
Does It Cost Anything, or Touch My Credit?
No, and no. It's free, and there's no credit pull. When the tool asks about your credit score, you're just telling it your range so it can match you to the right program. Whether you're sitting at an 800 or still rebuilding, I've got lenders for that. Nothing gets run, and nothing hits your report.
Just know going in that this is a preliminary estimate, not a loan commitment. It uses our own program pricing, calibrated to what our lenders charge, so the numbers are honest, but it isn't a lender quote and the final number can still move. I'll get to why near the end.
What to Have Ready
You don't need much. Before you start, just have a rough idea of:
- The property address and purchase price
- Your rehab budget
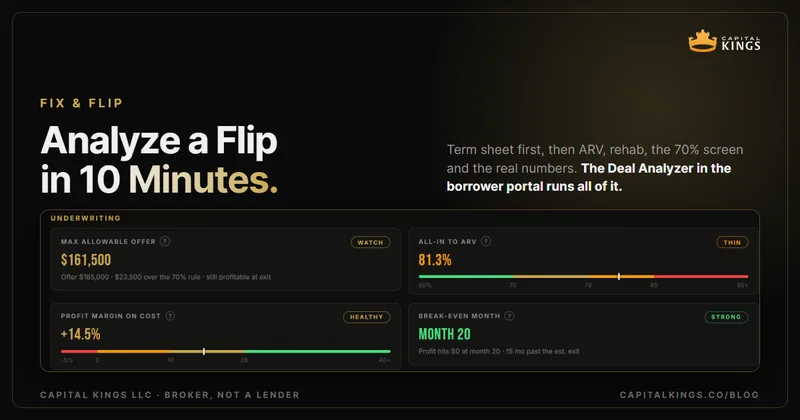
- Your after repair value (ARV) estimate, meaning what the property sells for once it's fixed up
- Roughly how much cash you've got to work with
- Your credit range and how many deals you've done
Don't have exact numbers yet? Estimate them. Running your deal math first helps, but you can change any of it later.
How to Get Yours in About 5 Minutes
Before you apply, you can test a deal right here. The mini term sheet below is the same one on our homepage. Drag a slider, or click any number and type your own, and everything underneath updates as you go.
The 90%, 95% and 100% buttons set how much of the purchase price the loan covers, and the rest is your down payment. The LTV bar compares your loan to the ARV. Once the loan would pass 75% of the ARV (70% at 100% financing), it gets capped there and your down payment goes up to cover the difference. The 95% and 100% options are the major Texas metro programs; outside Texas, a first flip starts at 10% down.
 Mini Term Sheet
Capital Kings LLC
Live
Nothing you type here gets saved. These numbers price a first deal at 700-759 credit on our Texas programs, where 95% and 100% of the purchase are available in the major metros. Other states price on their state page. When you apply, the full term sheet adds your rate, loan term and monthly payment, priced for your own credit and experience.
When you're ready for the full sheet you can save and download, here's how to get it:
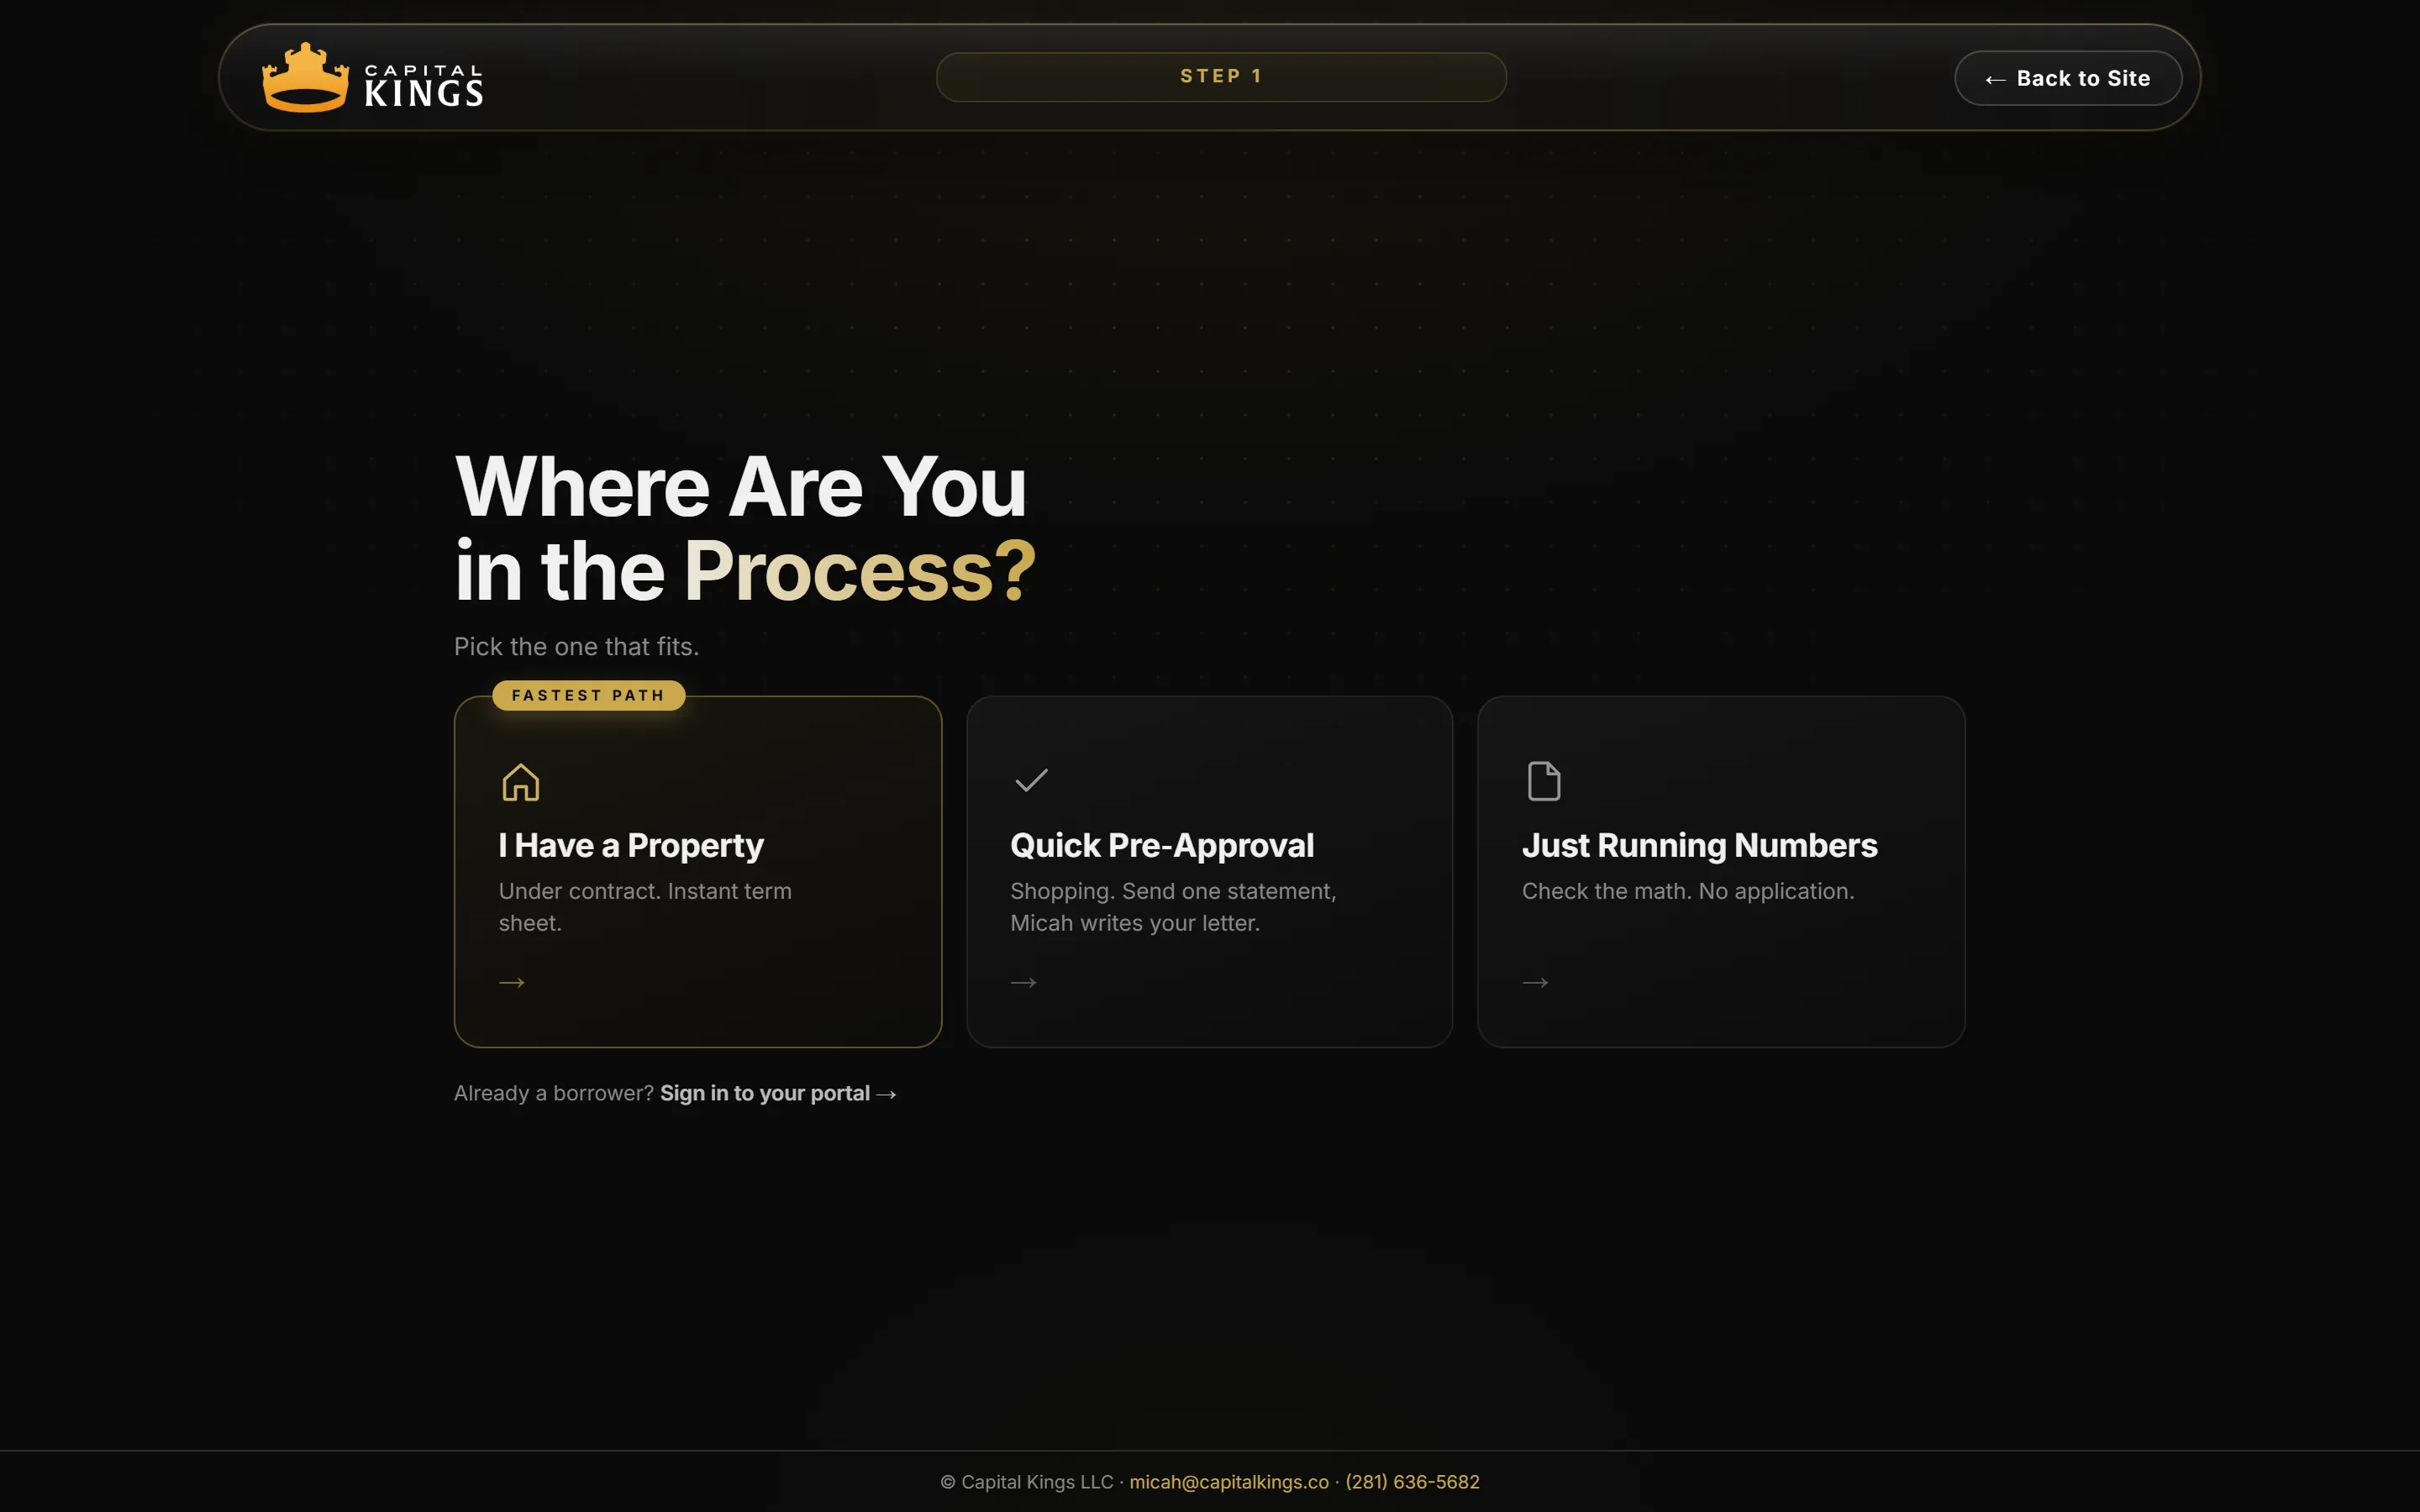
Start the application and pick your path
Head to the apply page. If you've already got a property under contract or picked out, choose "I have a property." If you're still shopping, the "Quick Pre-Approval" path is the one for you: I review it and reach out for one recent bank statement or a balance screenshot before your letter goes out.
Pick the loan and property type
Fix and flip, purchase-only, new construction, DSCR rental or cash-out, then the kind of property.
Drop in your deal numbers
Property address, purchase price, rehab budget, and your ARV estimate. It's the same info you'd give any lender. Your term sheet starts building live beside you as you answer.
Timeline, credit and experience
When you need to close and your exit, your estimated credit range (no credit pull), and how many deals you've done.
Choose your structure and show your funds
You'll see a set of programs, each priced for you. Less down keeps more cash in your pocket, and more down usually gets you a lower rate. Whichever one you pick is exactly what your term sheet shows. Then you tell it roughly what you have available to close.
Add your details last
Name, email, phone, your LLC if you have one, and a PIN. That saves the term sheet to your borrower portal, lets you view or download the PDF, and sends it to me.
Common Questions
Is an instant term sheet a real loan offer?
Will getting a term sheet run my credit?
How accurate is the instant term sheet?
What do I need to get a hard money term sheet?
Do I have to talk to anyone to get one?
Not sure a deal pencils out? Build the term sheet first, and then we can go over the numbers together. It won't cost you anything, and you'll know where you stand.