 Capital Kings LLC · Non-QM Mortgage Broker
Hard Money Lenders inGreat Falls, Montana
Fix and flip, DSCR rental and new construction financing for Great Falls investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
Price a Great Falls deal right now
Prefilled with a realistic Great Falls deal. Change any number and it reprices on the programs that lend in Montana, with the same math as our term sheets.
Sizing your flip on the same terms as the term sheet. Get a real term sheet →
Financing a deal in Great Falls
Great Falls sits on the Missouri River in north central Montana, and it is an Air Force town first. Malmstrom Air Force Base on the east edge, the regional hospital, agriculture and rail are what keep people buying here. Prices sit well below Bozeman and Missoula, and the flip stock is plentiful: early 1900s brick foursquares and bungalows on the Northside and Southside, and post-war ranches with basements spreading east toward the base.
Military moves set the rhythm of a Great Falls flip. Airmen arrive and leave on orders, many buy with VA loans, and the summer move season is when a finished house sells fastest. Time the listing for it if you can. The other deciding line is the basement. Most older houses here have one, and turning it into finished living space with a legal bedroom is the cheapest square footage you will add.
What a Great Falls deal looks like on paper
Great Falls example: $195,000 purchase, $50,000 rehab, $340,000 after repair value, 700 credit, 4+ completed flips. The engine puts that borrower on the 7.5% Down, 3+ Flips program at 9.99%. Picture a 1950s ranch on the east side near the base: roof, furnace, a basement bedroom with egress, kitchen and bath. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (7.5% of purchase plus rehab)You$18,375
- Origination (1.63%)Lender$3,683
- Lender fees (flat)Lender$2,790
- Broker fee (1%)Broker$2,266
- Title and closing (estimate at Texas rates)Title$3,456
- Prepaid interest (15 days)Lender$725
- Property insuranceInsurer$2,328
- AppraisalAppraiser$550
Interest while you rehab: $1,470 a month on the $176,625 funded at closing, $1,887 once every draw is out. Proof of funds is cash to close plus $13,500 of rehab reserve and $11,320 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
Fix and flip programs in Great Falls
Swipe the table for rates, credit and terms →
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Experienced Investor Rate1 | 15% of purchase | 680+ | 2+ completed flips | 9.00% | 0.75% | 75% of ARV | 12-24 months | 7-14 days |
| First Flip, 10% Down2 | 10% of purchase + rehab | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips3 | 7.5% of purchase + rehab | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 5+ Flips4 | 5% of purchase | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| 100% Financing, 2+ Flips5 | 0% (100% financing) | 620+ | 2+ completed flips | 9.50% to 12.00% | 2.5% | 70% of ARV | 9 months | 7-14 days |
- Rate and origination are the program floor; two completed projects in the last 36 months preferred.
- Rate 9.99% with 2% to 2.25% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% with 1.5% to 1.75% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
- Needs 2 completed flips in the last two years and about $75,000 in verified liquidity. Rate 9.5% to 12% with 2% to 3% origination, set per file. Purchase plus rehab must fit under 70% of ARV.
Origination has a $2,000 minimum on most programs (a few lenders set a higher one, noted above) and our broker fee is 1% with a $2,000 minimum and a $10,000 maximum. These are the numbers our term sheets use as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
Where Great Falls prices sit right now
Before we price a Great Falls flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the Great Falls median sale price at $350K for the three months ending September 2026, up 5.6% from a year earlier, with homes selling after about 51 days on the market.
| Median sale price, Great Falls (Redfin, 3 months to Sep 2026) | $350K |
| Days on market, Great Falls (Redfin) | 51 |
| Year over year change in median (Redfin) | +5.6% |
Sources: Redfin, Great Falls housing market
How a Great Falls file actually gets priced
Montana is a non-disclosure state, so sale prices are not on public record and the appraiser works from MLS data. Great Falls comps stay on their own side of the river and their own era of house: a Northside foursquare is not valued against an east side ranch. We use closed MLS sales from the last few months, check whether the basement in each comp is finished, and watch for comps that sold to a buyer on orders in a hurry, since those can run high.
Winters are long and the Chinook winds swing temperatures fast, which is hard on roofs, siding and pipes. Hail is a regular insurance claim. Older brick houses can hide foundation movement, failing sewer lines and outdated wiring, and the Missouri and its tributaries have mapped floodplains along the lower parts of town. Permits run through the City of Great Falls, and the short building season means exterior work should be scheduled early.
Who buys your finished Great Falls deal
Finished Great Falls flips go to military families, hospital staff and local first-time buyers, and a large share use VA or FHA, so the house has to pass an appraiser’s condition review. Montana has no general sales tax, which keeps materials a little cheaper than in neighboring states. If the sale market slows, the base keeps rental demand steady, and a DSCR refinance is a solid backup.
What happens after you apply
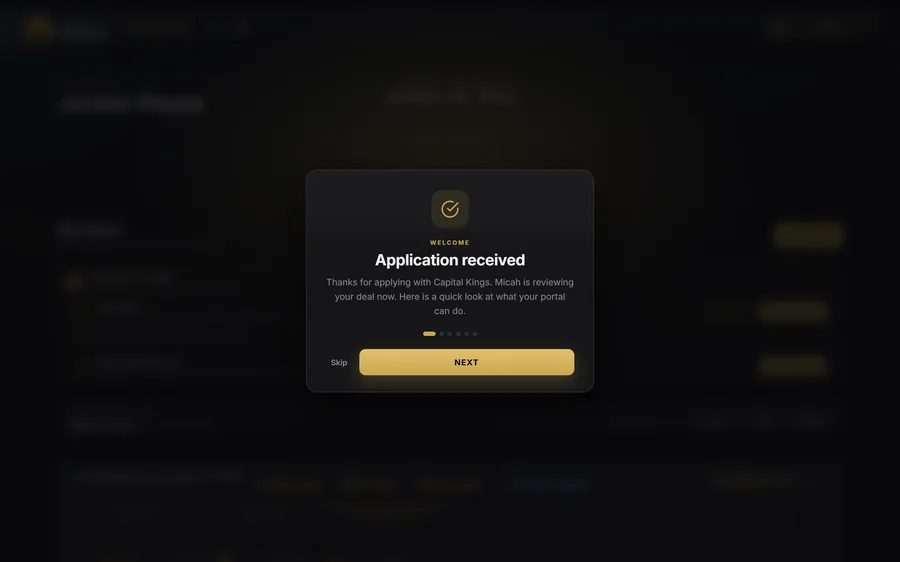
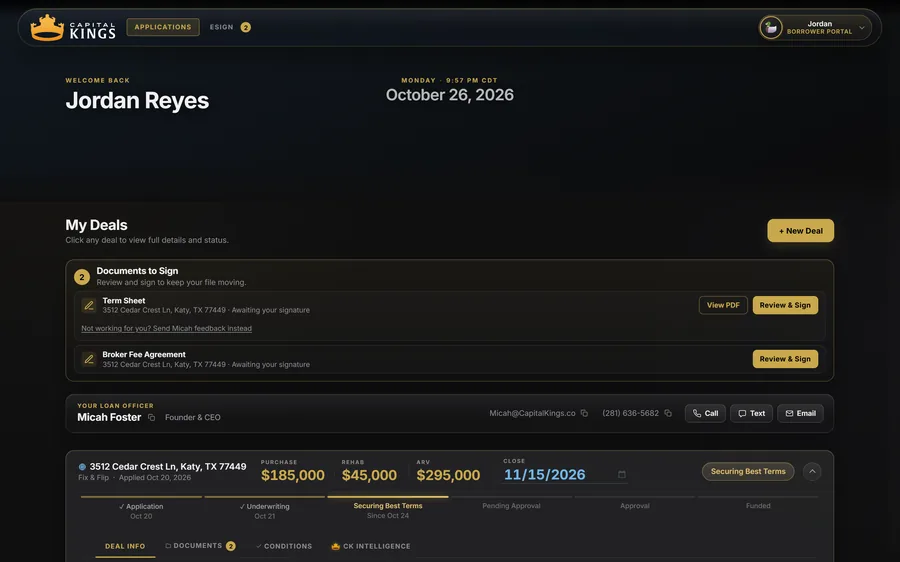
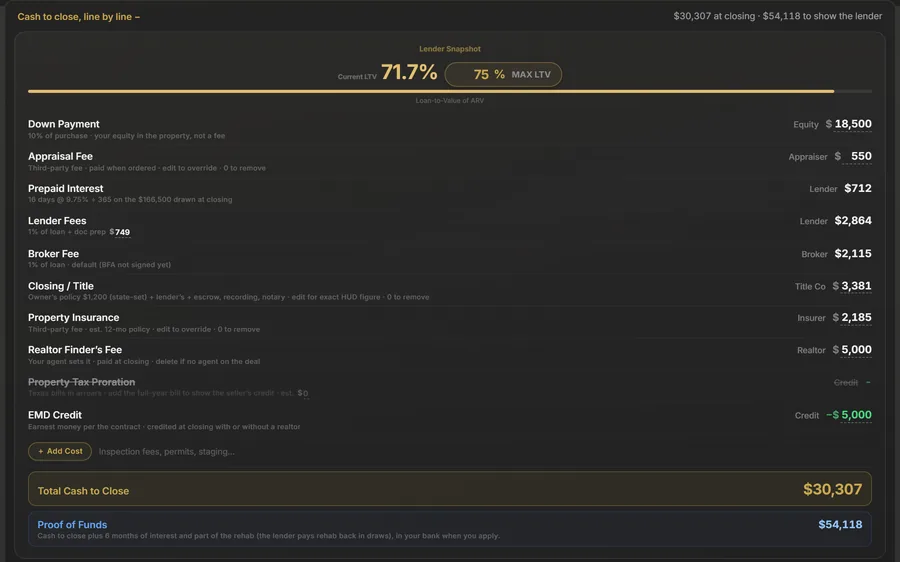
Apply once and the whole Great Falls loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
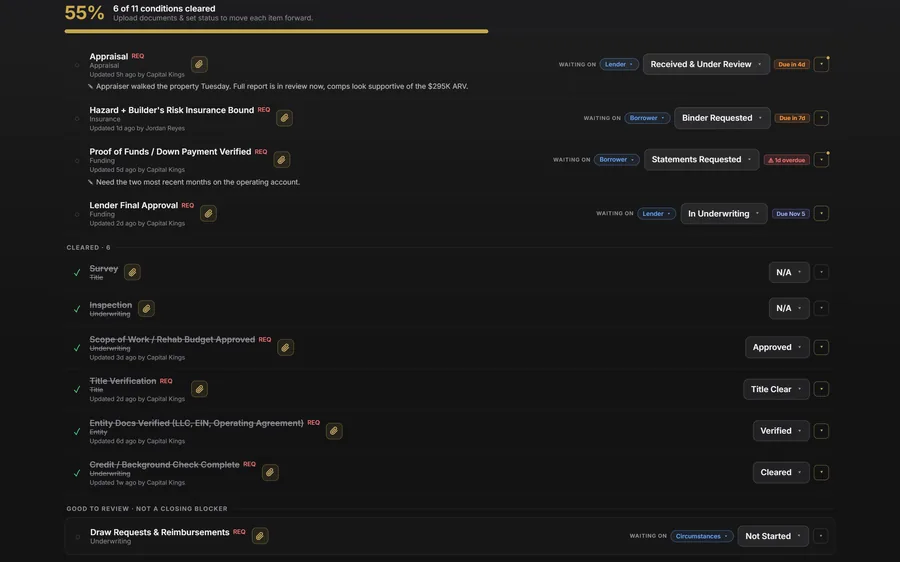
The full walkthrough is on how it works, and you can tour the borrower portal before you apply.
What we fund in Great Falls
Fix and flip
- Rates
- from 9.00% at 680+ credit with 2+ completed flips
- With experience
- 0% down with 2+ completed flips, purchase plus rehab under 70% of ARV
- Rehab
- 100% funded, paid in draws
Rental (DSCR)
- Qualify on
- the rent, no W-2s or tax returns
- Down
- from 20% at 700+ credit
- Good for
- buy-and-hold, and the refinance when a flip becomes a rental
New construction
- Rates
- from 8.49% with 5+ completed builds
- First build
- 85% of cost with a GC who has 5+ builds
- Builds
- single family to small multifamily
Where we lend in Great Falls
We broker deals across the whole Great Falls market. The submarkets investors ask us about most are Northside historic district (59401), Southside (59405), East side toward Malmstrom (59405), Westside across the Missouri (59404), Black Eagle (59414) and Riverview and the north end (59404).
How long does a Great Falls loan take to fund?
You send the address, purchase price, rehab budget and your ARV, which takes about five minutes and no credit pull. We take it to the lenders in our network that fit it and are licensed in Montana, and the rate, origination, leverage and cash to close come back side by side. Plan on 7-14 days with completed flips and 21-30 days on a first flip. We stay on title and the lender through funding.
Great Falls hard money FAQ
Do you lend hard money in Great Falls?
Which fix and flip programs apply in Great Falls?
How fast can a Great Falls hard money loan close?
How much do I need to bring to close on a Great Falls flip?
Do you fund the rehab budget in Great Falls?
What credit score do I need for a Great Falls fix and flip loan?
Can I refinance a Great Falls flip into a rental loan?
When is the best time to list a Great Falls flip?
Do you lend to first-time flippers in Great Falls?
What to read before you sign a term sheet
- Dutch vs standard interest: what it really costs you
- Cash to close on a flip: the number most investors miss
- How to get an instant hard money term sheet
- Direct hard money lender vs broker: the honest breakdown
Hard money near Great Falls: Billings and Helena. More Montana city guides: Bozeman and Missoula. Or see everything we fund in Montana.
Ready to fund your Great Falls deal?
Submit your scenario in about 5 minutes. We shop it and come back with real terms, not a generic rate sheet.