 Capital Kings LLC · Non-QM Mortgage Broker
Hard Money Lenders inDallas, Texas
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for Dallas investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
Price a Dallas deal right now
Prefilled with a realistic Dallas deal. Change any number and it reprices on the programs that lend in Texas, with the same math as our term sheets.
Sizing your flip on the same terms as the term sheet. Get a real term sheet →
Financing a deal in Dallas
Dallas is a smaller part of our book than Houston, and the mix is different: more of the scenarios that come to us out of DFW are rental and DSCR plays rather than flips, and the price points run higher on both ends. We are straight about that rather than pretending the footprint is the same.
Dallas rewards precision on the exit more than Houston does. The gap between a Lakewood rehab and a South Dallas rehab is not just price, it is buyer type, days on market, and whether a DSCR refinance is realistically available at the end. Because the spread between purchase and finished value runs wider here, lenders scrutinize the ARV harder, and an aggressive number is the most common reason a DFW file gets repriced late. We would rather set a conservative ARV on day one and hold it.
What a Dallas deal looks like on paper
Dallas example: $272,500 purchase, $90,000 rehab, $500,000 after repair value, 700 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$40,875
- Origination (0.5%)Lender$2,000
- Lender fees (flat)Lender$1,989
- Broker fee (1%)Broker$3,216
- Title and closingTitle$3,925
- Prepaid interest (15 days)Lender$903
- Property insuranceInsurer$3,444
- AppraisalAppraiser$550
Interest while you rehab: $1,832 a month on the $231,625 funded at closing, $2,544 once every draw is out. Proof of funds is cash to close plus $22,500 of rehab reserve and $15,261 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
Fix and flip programs in Dallas
Swipe the table for rates, credit and terms →
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% of purchase | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 70% of ARV | 12 months | 5-14 days |
| New Investor Program | 12.5% of purchase | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| First Flip, 10% Down1 | 10% of purchase + rehab | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| Best Value | 5% of purchase | 590+ | First flip OK | 9.99% to 12.99% | 2% | 75% of ARV | 12 months | 5-14 days |
| 7.5% Down, 3+ Flips2 | 7.5% of purchase + rehab | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 5+ Flips3 | 5% of purchase | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| Lowest Down (100% financing) | 0% (100% financing) | No minimum | First flip OK | 11.50% | 3% | 70% of ARV | 6 months | 5-14 days |
| Fastest Close (3 days) | 10% of purchase | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Rate 9.99% with 2% to 2.25% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% with 1.5% to 1.75% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on most programs (a few lenders set a higher one, noted above) and our broker fee is 1% with a $2,000 minimum and a $10,000 maximum. These are the numbers our term sheets use as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network.
How a Dallas file actually gets priced
DFW files draw more scrutiny on the ARV than Houston files do, because the spread between purchase and finished value tends to run wider here and lenders know it. An aggressive number is the most common reason a Dallas file gets repriced at the eleventh hour. We would rather set the ARV conservatively on day one and hold it through underwriting than book a headline number that gets cut the week of closing.
The DFW scenarios that reach us skew toward rental and DSCR rather than flips, and that is worth treating as a signal rather than a coincidence. If a deal only works when you assume a fast retail resale, but the same property pencils comfortably as a hold, the market is telling you which strategy it prefers. Run both before you commit, because refinancing into a DSCR loan at the end is a very different underwrite than selling.
Who buys your finished Dallas deal
The exit varies more by pocket in Dallas than almost anywhere we lend. A Lakewood or M Streets rehab exits to a retail buyer quickly and at a high number. The same rehab budget in a transitional South Dallas pocket exits slower, to a different buyer, and is far more likely to become a rental hold. Decide which of those you are underwriting before you make the offer, because it changes both the finish level and the financing you should be using.
What a typical Dallas flip looks like
| A typical Dallas deal | Range |
|---|---|
| Purchase price | $95,000 to $450,000 |
| After repair value | $315,000 to $850,000 |
| Most common loan type | Fix & Flip |
The range that is common on Dallas deals, as of August 2026. Bring us something outside it and we will still price it, the range is what is common here, not a cap.
What happens after you apply
Apply once and the whole Dallas loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
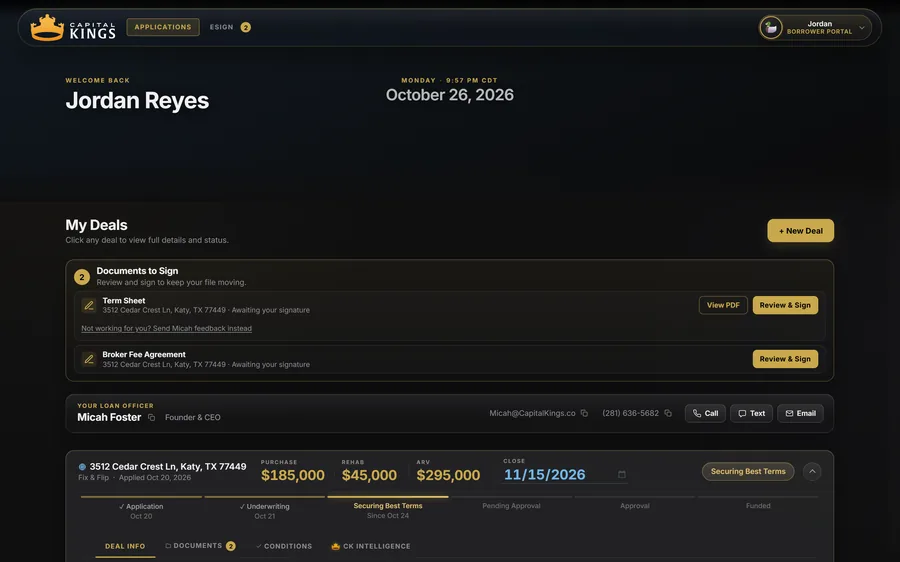
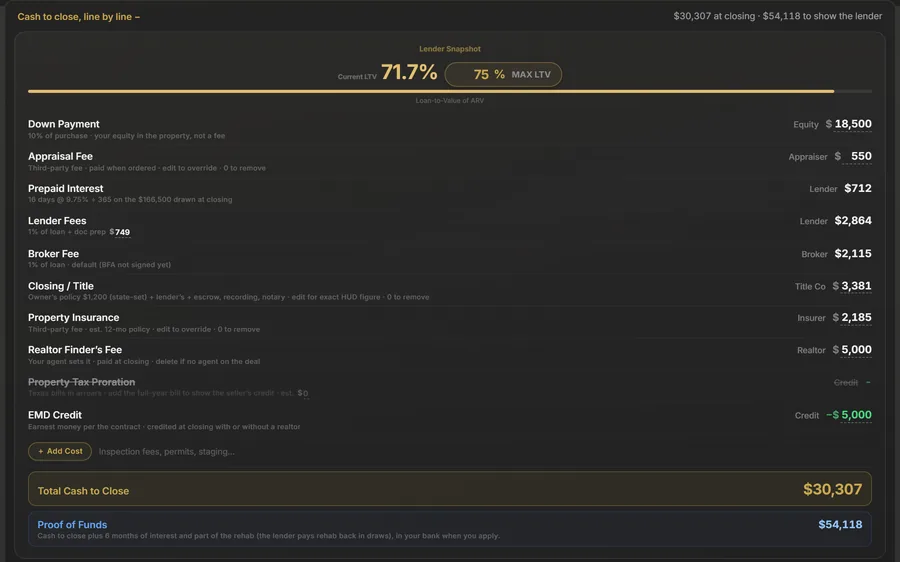
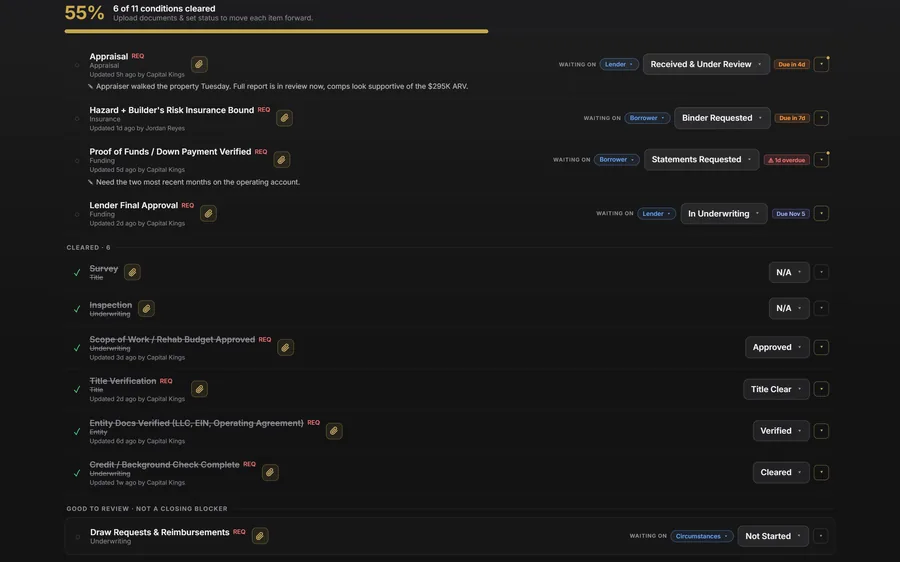
The full walkthrough is on how it works, and you can tour the borrower portal before you apply.
What we fund in Dallas
Fix and flip
- Rates
- from 8.99% at 760+ credit
- Max loan
- up to 75% of ARV
- Rehab
- 100% funded, paid in draws
Rental (DSCR)
- Qualify on
- the rent, no W-2s or tax returns
- Down
- from 20% at 700+ credit
- Good for
- buy-and-hold, and the refinance when a flip becomes a rental
Bridge and purchase only
- Rates
- from 9.75% at 680+ credit
- Close
- in 5-14 days
- Good for
- auction buys, off-market deals and 1031 timing
New construction
- Rates
- from 8.49% with 5+ completed builds
- First build
- 85% of cost with a GC who has 5+ builds
- Builds
- single family to small multifamily
Where we lend in Dallas
We broker deals across the whole Dallas market. The submarkets investors ask us about most are Lakewood (75214), M Streets (75206), Downtown / Deep Ellum (75201), South Dallas (75215), Lake Highlands (75238) and Vickery Meadow (75243).
How long does a Dallas loan take to fund?
You send the address, purchase price, rehab budget and your ARV, which takes about five minutes and no credit pull. We take it to the lenders in our network that fit it and are licensed in Texas, and the rate, origination, leverage and cash to close come back side by side. 5-14 days to fund, as little as 72 hours on the fastest programs. We stay on title and the lender through funding.
Dallas hard money FAQ
Do you lend hard money in Dallas?
Which fix and flip programs apply in Dallas?
How fast can a Dallas hard money loan close?
How much do I need to bring to close on a Dallas flip?
Do you fund the rehab budget in Dallas?
What credit score do I need for a Dallas fix and flip loan?
Do you do DSCR rental loans in Dallas?
Should I flip or hold a Dallas investment property?
Do you fund DSCR rental loans in Dallas?
What to read before you sign a term sheet
- Points, fees & rate: how to compare hard money lenders
- How construction draws and the rehab holdback actually work
- Dutch vs standard interest: what it really costs you
- Cash to close on a flip: the number most investors miss
We also have DSCR loans in Dallas and new construction loans in Dallas. Hard money near Dallas: Houston and Shreveport. More Texas city guides: Arlington, Austin, Corpus Christi, Cypress, El Paso, Fort Worth, Frisco, Katy, Lubbock, McKinney, Plano, San Antonio, Spring and The Woodlands. Or see everything we fund in Texas.
Ready to fund your Dallas deal?
Submit your scenario in about 5 minutes. We shop it and come back with real terms, not a generic rate sheet.