 Capital Kings LLC · Non-QM Mortgage Broker
Hard Money Lenders inCorpus Christi, Texas
Fix and flip, bridge and purchase only, DSCR rental and new construction financing for Corpus Christi investors. We do not lend our own money, we shop your deal across a 400+ lender network and come back with real terms you can compare on total cost.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
Price a Corpus Christi deal right now
Prefilled with a realistic Corpus Christi deal. Change any number and it reprices on the programs that lend in Texas, with the same math as our term sheets.
Sizing your flip on the same terms as the term sheet. Get a real term sheet →
Financing a deal in Corpus Christi
Corpus Christi is a Gulf port city with entry prices well under the big Texas metros and a buyer base built on the Navy, the refineries, the port and Texas A&M University Corpus Christi. Most flips are 1950s to 1970s brick and frame ranches in Midtown and on the Westside, bought from estates and long-time owners and finished for a first-time buyer. The Southside is newer and pricier, and the island is its own market of condos and second homes.
Two coastal rules decide a Corpus deal before the kitchen does. Every roof, window or door replaced here falls under the Texas windstorm program, so the work needs an inspection and a WPI-8 certificate of compliance or the next owner cannot keep wind coverage through TWIA, the state’s windstorm pool. Skip the certificate and your buyer’s insurance agent finds out at closing. The second is water. The city spent almost 600 days under Stage 3 drought rules before easing to Stage 2 in August 2026, and buyers and landscapers both noticed. Budget xeriscape rather than new sod, and know the water story when a buyer asks.
What a Corpus Christi deal looks like on paper
Corpus Christi example: $140,000 purchase, $45,000 rehab, $245,000 after repair value, 700 credit, first flip. The engine puts that borrower on the Best Rate program at 9.49%. Picture a 1960s brick ranch in Midtown off Weber Road: new roof with its windstorm certificate, kitchen, baths, flooring and a cast iron drain line swapped for PVC. Every number below is what the instant term sheet prints for that deal, so the picture cannot contradict the page.
- Down payment (15% of the purchase)You$21,000
- Origination (0.5%)Lender$2,000
- Lender fees (flat)Lender$1,989
- Broker fee (1%)Broker$2,000
- Title and closingTitle$3,146
- Prepaid interest (15 days)Lender$464
- Property insuranceInsurer$1,758
- AppraisalAppraiser$550
Interest while you rehab: $941 a month on the $119,000 funded at closing, $1,297 once every draw is out. Proof of funds is cash to close plus $13,500 of rehab reserve and $7,782 of interest reserve. Sample borrower, sample address; the sheet is issued by the same engine as the borrower’s instant term sheet.
Fix and flip programs in Corpus Christi
Swipe the table for rates, credit and terms →
| Program | Down payment | Min credit | Experience | Rate | Origination | Max loan | Term | Close |
|---|---|---|---|---|---|---|---|---|
| Best Rate | 15% of purchase | 700+ | First flip OK | 8.99% to 9.49% | 0.5% | 70% of ARV | 12 months | 5-14 days |
| New Investor Program | 12.5% of purchase | 700+ | First flip OK | 9.75% | 1% | 75% of ARV | 12 months | 72 hours |
| First Flip, 10% Down1 | 10% of purchase + rehab | 660+ | First flip OK | 9.99% | 2% | 75% of ARV | 12 months | 21-30 days |
| 7.5% Down, 3+ Flips2 | 7.5% of purchase + rehab | 660+ | 3+ completed flips | 9.99% | 1.5% | 75% of ARV | 12 months | 21-30 days |
| 5% Down, 5+ Flips3 | 5% of purchase | 660+ | 5+ completed flips | 9.99% to 10.99% | 2% | 75% of ARV | 9-24 months | 10-14 days |
| Fastest Close (3 days) | 10% of purchase | No minimum | First flip OK | 11.99% | 2% | 75% of ARV | 6 months | 72 hours |
- Rate 9.99% with 2% to 2.25% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 87.5% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate 9.99% with 1.5% to 1.75% origination by credit; more origination buys the rate down as far as 8.99%. Loans under $150,000 add 0.5% to the rate and 0.5% to the origination, under $100,000 1.5% and 1%. Under 680 credit the loan caps at 90% of cost. Standard interest, charged only on funds drawn. The loan is capped at a share of purchase plus rehab, the full rehab held back for draws, and the ARV must be at least 1.25 times purchase plus rehab. Processing $500, legal $1,495 and underwriting $795.
- Rate is set per file from 9.99%; origination about 2% plus a $995 processing fee.
Origination has a $2,000 minimum on most programs (a few lenders set a higher one, noted above) and our broker fee is 1% with a $2,000 minimum and a $10,000 maximum. These are the numbers our term sheets use as of October 2026. Strong credit, cash and a track record can price lower through specific lenders in the network. The 5% down and 100% financing lanes are major-metro programs and are not shown for Corpus Christi.
Where Corpus Christi prices sit right now
Before we price a Corpus Christi flip, we look at where sales in the city sit today. Your block can run well above or below these numbers, so treat them as the starting point, not the answer.
Redfin puts the Corpus Christi median sale price at $270,000 for the three months ending September 2026, down 0.25% from a year earlier, with homes selling after 68 days on market. Zillow’s average home value for the city is $222,115, up 0.6% over the past year. Midtown’s 78411 runs under the city number at a $202,000 Redfin median, selling in 37 days.
| Median sale price, Corpus Christi (Redfin, 3 months to Sep 2026) | $270,000 |
| Days on market, Corpus Christi (Redfin) | 68 |
| Zillow home value, Corpus Christi (Sep 2026) | $222,115 |
| Median sale price, 78411 Midtown (Redfin) | $202,000 |
| Days on market, 78411 (Redfin) | 37 |
Sources: Redfin, Corpus Christi housing market, Zillow, Corpus Christi home values, Redfin, 78411 housing market, TWIA, windstorm certification
How a Corpus Christi file actually gets priced
The Corpus file gets priced pocket by pocket, because the city is long and the price lines are sharp. A Southside comp off Saratoga will not carry a Westside house, and Midtown streets near Ocean Drive sell for more than streets near the crosstown expressway. We pull closed sales from the last 90 days inside the same pocket and the same vintage, we check whether the comp had a windstorm certificate on its roof, and on a slab from the 1960s we want a plumbing scope, because cast iron under the house is the line item that shows up after the tile is laid.
Hurricane exposure is the Corpus Christi insurance question. Nueces County is a designated catastrophe area, so TWIA writes the wind coverage, private carriers write the rest, and premiums plus a percentage wind deductible belong in your carry. Low streets near Oso Bay, the bayfront and Flour Bluff carry flood zones and surge risk; pull the FIRM panel before you write the offer. Salt air is hard on HVAC coils and exterior metal, and the clay under much of the city moves between drought and heavy rain, so cracks in brick veneer get a foundation look. Permits run through the city’s Development Services, and the windstorm inspection is a separate step from the city inspection.
Who buys your finished Corpus Christi deal
A finished Midtown or Westside house sells to a first-time buyer, often military from the Naval Air Station or the Army depot, a refinery worker or a nurse at one of the hospital systems, and plenty of them use FHA or VA. That means the house has to clear a government appraisal: working HVAC, sound roof with its certificate, no peeling paint on older stock. The Southside exit is a move-up family comparing your house to new builds farther south. Days on market run longer here than in the big metros, so plan the carry for it, and keep the rental math handy, because a DSCR refinance works on a lot of Corpus addresses.
What happens after you apply
Apply once and the whole Corpus Christi loan lives in the borrower portal: the term sheet you can accept and sign in the browser, where the loan stands, one place for documents, and the list of what the lender is still waiting on. These are real screens from the portal.
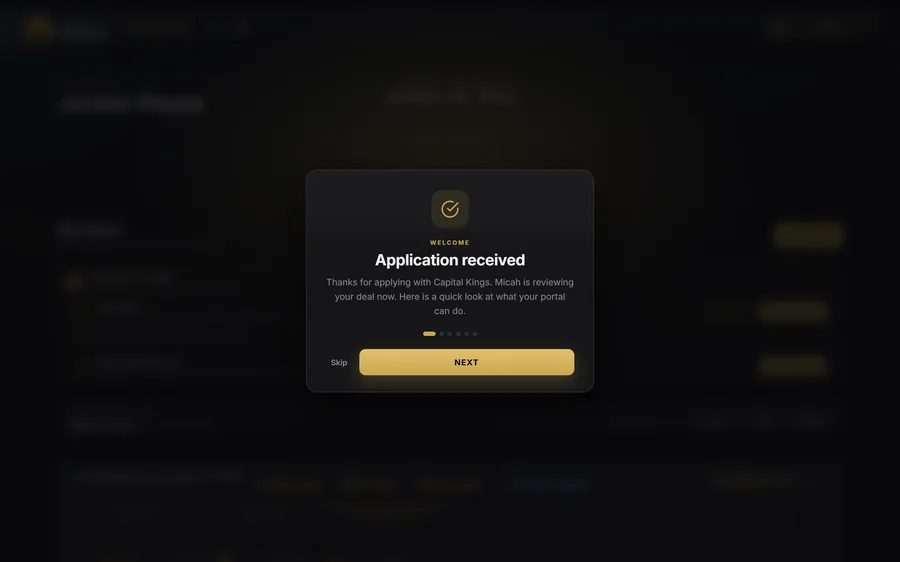
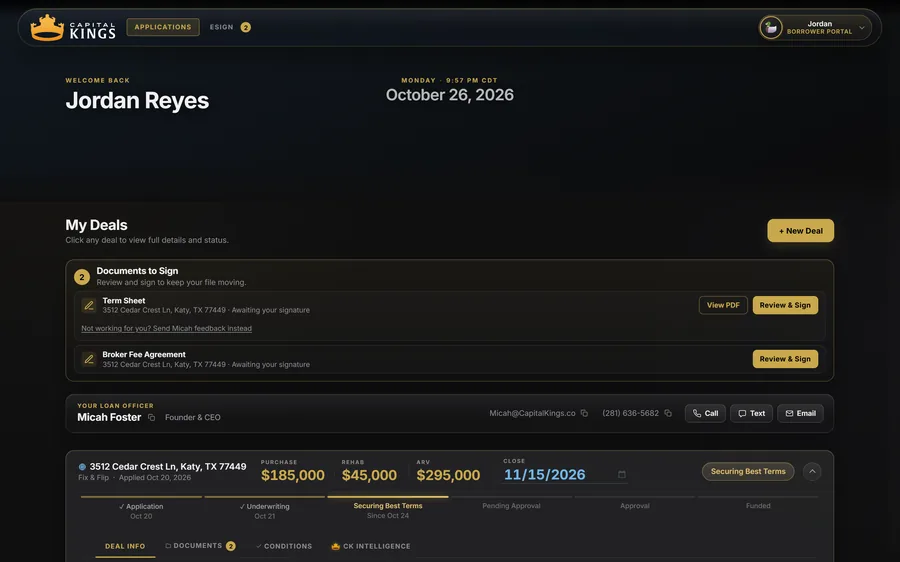
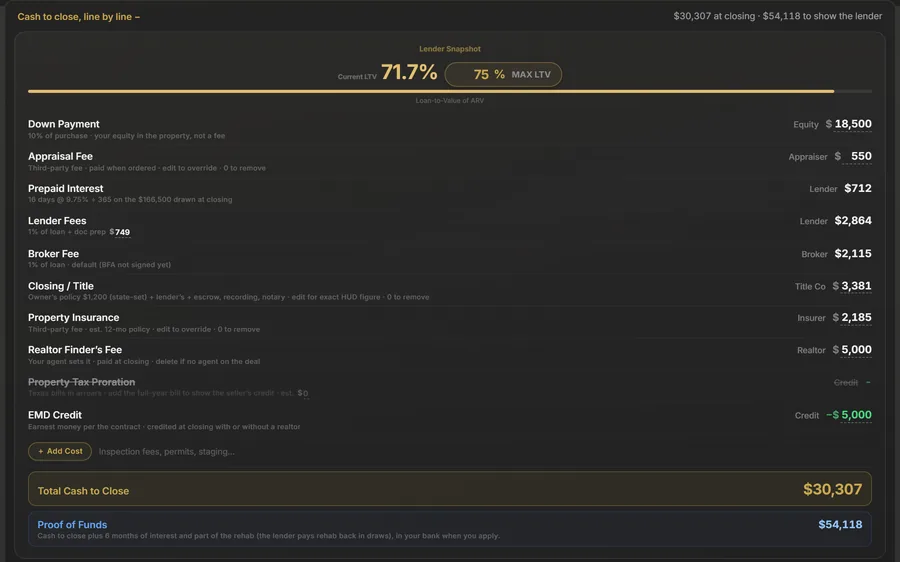
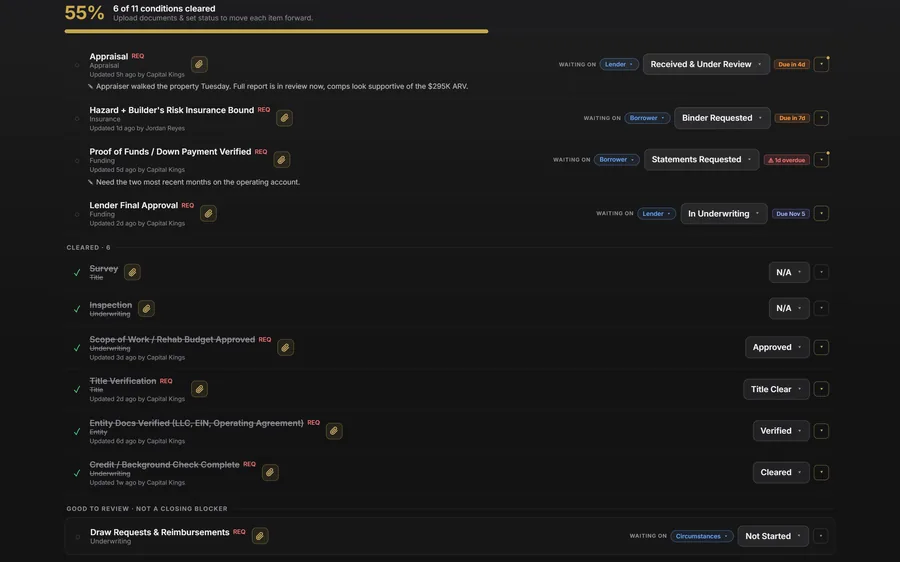
The full walkthrough is on how it works, and you can tour the borrower portal before you apply.
What we fund in Corpus Christi
Fix and flip
- Rates
- from 8.99% at 760+ credit
- With experience
- 5% down with 5+ completed flips
- Rehab
- 100% funded, paid in draws
Rental (DSCR)
- Qualify on
- the rent, no W-2s or tax returns
- Down
- from 20% at 700+ credit
- Good for
- buy-and-hold, and the refinance when a flip becomes a rental
Bridge and purchase only
- Rates
- from 9.75% at 680+ credit
- Close
- in 5-14 days
- Good for
- auction buys, off-market deals and 1031 timing
New construction
- Rates
- from 8.49% with 5+ completed builds
- First build
- 85% of cost with a GC who has 5+ builds
- Builds
- single family to small multifamily
Where we lend in Corpus Christi
We broker deals across the whole Corpus Christi market. The submarkets investors ask us about most are Midtown off Weber and Staples (78411 / 78412), Southside toward Saratoga (78413 / 78414), Flour Bluff near the Naval Air Station (78418), Calallen and Northwest (78410), Westside off Leopard and Baldwin (78415 / 78416) and Padre and Mustang Island (78418).
How long does a Corpus Christi loan take to fund?
You send the address, purchase price, rehab budget and your ARV, which takes about five minutes and no credit pull. We take it to the lenders in our network that fit it and are licensed in Texas, and the rate, origination, leverage and cash to close come back side by side. 5-14 days to fund, as little as 72 hours on the fastest programs. We stay on title and the lender through funding.
Corpus Christi hard money FAQ
Do you lend hard money in Corpus Christi?
Which fix and flip programs apply in Corpus Christi?
How fast can a Corpus Christi hard money loan close?
How much do I need to bring to close on a Corpus Christi flip?
Do you fund the rehab budget in Corpus Christi?
What credit score do I need for a Corpus Christi fix and flip loan?
Can I refinance a Corpus Christi flip into a rental loan?
Do I need a windstorm certificate on a Corpus Christi flip?
What programs fit a Corpus Christi flip if the 5% down and 100% financing options are not shown?
What to read before you sign a term sheet
- Points, fees & rate: how to compare hard money lenders
- How construction draws and the rehab holdback actually work
- Dutch vs standard interest: what it really costs you
- Cash to close on a flip: the number most investors miss
Hard money near Corpus Christi: San Antonio and Houston. More Texas city guides: Arlington, Austin, Cypress, Dallas, El Paso, Fort Worth, Frisco, Katy, Lubbock, McKinney, Plano, Spring and The Woodlands. Or see everything we fund in Texas.
Ready to fund your Corpus Christi deal?
Submit your scenario in about 5 minutes. We shop it and come back with real terms, not a generic rate sheet.